The Insider’s Guide to Car Sales Information: What Buyers Really Need to Know
Table of Contents
- The Complete Overview of Car Sales Information
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: How can I verify a dealer’s advertised price against the actual invoice price?
- Q: Are "out-the-door" prices from online marketplaces accurate?
- Q: Can I negotiate the destination fee on a new car?
- Q: How do I check if a used car’s price matches its market value?
- Q: What’s the best way to avoid dealer upsells on add-ons?
- Q: How do I leverage car sales information to get a better trade-in offer?
- Q: Are there any red flags in car sales information that signal a bad deal?
The car sales process isn’t just about test drives and handshakes—it’s a carefully orchestrated exchange of car sales information where transparency often takes a backseat to profit margins. Behind every sticker price lies a web of dealer costs, manufacturer incentives, and regional market fluctuations that most buyers overlook. Understanding these dynamics isn’t just about saving money; it’s about gaining leverage in an industry where misinformation can cost thousands.
Consider this: A 2023 Consumer Reports study found that 68% of new car buyers admitted to leaving money on the table due to poor preparation. The gap between what dealers disclose and what consumers uncover—often through third-party tools or industry insiders—can be staggering. Whether you’re eyeing a Tesla Model 3 or a pre-owned Subaru Outback, the ability to decode car sales information separates the savvy buyer from the one who walks away with buyer’s remorse.
Yet, the real challenge isn’t just accessing data—it’s interpreting it. Dealerships rely on psychological pricing, rebate stacking, and add-on tactics that obscure the true cost of ownership. Even online marketplaces, while convenient, often lack the granularity of invoice pricing, holdback percentages, or regional demand trends. The result? Buyers make decisions based on surface-level car sales information while dealers capitalize on information asymmetry.
The Complete Overview of Car Sales Information
The modern car sales ecosystem operates on three pillars: transparency, negotiation leverage, and post-purchase clarity. Transparency, however, remains the most elusive. Dealers are legally required to disclose certain details—like vehicle history for used cars or warranty terms—but the fine print often buries critical costs (e.g., destination fees, doc fees, or mandatory add-ons like paint protection). Meanwhile, negotiation leverage hinges on a buyer’s ability to cross-reference car sales information from multiple sources: manufacturer invoices, Edmunds/Kelley Blue Book valuations, and even competitor dealerships’ advertised prices.
What’s less discussed is the role of car sales information in the post-purchase phase. A well-informed buyer doesn’t just secure a better price; they avoid hidden fees during service visits, understand resale depreciation curves, and even anticipate recall campaigns. The most strategic buyers treat car purchases as long-term financial decisions, not just transactions. This shift requires dissecting not just the upfront cost, but the total cost of ownership—fuel efficiency, maintenance schedules, and even state-specific taxes.
Historical Background and Evolution
The car sales industry’s relationship with transparency has evolved alongside consumer protection laws. In the early 20th century, dealers operated with near-total opacity, selling cars as "as-is" with minimal disclosure. The 1970s brought the first federal regulations, including the Magnuson-Moss Warranty Act (1975), which standardized warranty terms. However, it wasn’t until the 2000s—with the rise of online marketplaces like Autotrader and TrueCar—that car sales information became somewhat democratized. These platforms forced dealers to compete on price transparency, albeit with limitations (e.g., "out-the-door" pricing that excluded add-ons).
Today, the industry is at a crossroads. On one hand, tech-driven tools (e.g., CarGurus’ "Fair Purchase Price" or Black Book’s auction data) provide buyers unprecedented access to car sales information. On the other, dealers have adapted by shifting profits to "admin fees," "dealer prep," or financing markups—areas where regulatory oversight is thinner. The evolution of car sales isn’t just about digital transformation; it’s a cat-and-mouse game between consumer demand for clarity and dealer strategies to obscure it.
Core Mechanisms: How It Works
At its core, car sales information functions as a negotiation currency. Dealers start with the manufacturer’s suggested retail price (MSRP), but their actual cost—the invoice price—is often 10–20% lower due to rebates, holdbacks (funds retained by dealers), and fleet discounts. The art of car sales lies in bridging this gap without revealing the full invoice to the buyer. For example, a dealer might advertise a $30,000 car at MSRP but negotiate internally with the manufacturer to reduce their cost to $26,000—leaving a $4,000 buffer to absorb buyer discounts, add-ons, or profit.
Used cars introduce another layer: auction pricing, trade-in valuations, and dealer "cooking" (inflating mileage or repair costs). Here, car sales information becomes a puzzle. A car listed at $15,000 might have sold at auction for $12,000, with the dealer adding $3,000 in "reconditioning" fees. Tools like Carfax or the National Automobile Dealers Association (NADA) guides can reveal these discrepancies, but they require buyers to ask the right questions—and dealers often deflect with vague answers like "market adjustments."
Key Benefits and Crucial Impact
The ability to navigate car sales information isn’t just about saving a few thousand dollars; it’s about reclaiming control in a high-stakes transaction. Buyers who arm themselves with data avoid emotional decisions, such as falling for low monthly payments that hide inflated interest rates or long loan terms. For businesses, fleet managers, or repeat buyers, this knowledge translates to bulk purchasing power, better trade-in offers, and even industry-specific incentives (e.g., tax write-offs for commercial vehicles).
Yet, the impact extends beyond the individual. Transparent car sales information pressures dealers to compete on fairness, not just price. When buyers demand invoice pricing or third-party appraisals, the market shifts toward accountability. This ripple effect has already led to states like California mandating "clean" pricing disclosures, where all fees must be itemized upfront. The long-term goal? An industry where car sales information is as standard as the VIN number.
"The dealer’s job isn’t to sell you a car—it’s to sell you a lifestyle. The car is just the hook." — Automotive Industry Analyst, 2024
Major Advantages
- Price Accuracy: Cross-referencing car sales information from Kelley Blue Book, Edmunds, and dealer invoices can reveal discrepancies of $1,000–$5,000 on new cars and $500–$2,000 on used ones.
- Add-On Avoidance: Dealers profit an average of 30–50% on extended warranties, paint protection, and gap insurance. Armed with car sales information, buyers can decline these or purchase them independently at lower rates.
- Financing Leverage: Knowing a dealer’s floor rate (the lowest APR they offer) allows buyers to negotiate below market rates or walk to competitors with better offers.
- Trade-In Optimization: Tools like Black Book or Trade-In Value apps provide real-time car sales information to ensure dealers aren’t lowballing offers by 15–25%.
- Resale Protection: Understanding depreciation curves (e.g., luxury cars lose 50%+ of value in 3 years) helps buyers choose models with better long-term car sales information transparency.
Comparative Analysis
| Aspect | Dealer-Led Sales | Online Marketplaces (e.g., CarGurus, TrueCar) |
|---|---|---|
| Transparency Level | Low to moderate; relies on verbal negotiation and hidden fees. | Moderate; "out-the-door" pricing but may exclude add-ons. |
| Access to Car Sales Information | Limited unless buyer demands invoice or third-party appraisal. | Better; provides average transaction prices but lacks dealer-specific data. |
| Negotiation Power | High for buyers with external car sales information (e.g., invoice pricing). | Low; prices are often fixed or based on algorithms. |
| Post-Purchase Support | Full service but may upsell unnecessary repairs. | Limited; relies on manufacturer warranties or third-party providers. |

Future Trends and Innovations
The next decade of car sales information will be shaped by blockchain and AI-driven transparency. Imagine a system where every vehicle’s history—from accident reports to service logs—is recorded on an immutable ledger, accessible to buyers in real time. Startups like Token are already piloting digital car titles that eliminate fraud and streamline sales. Meanwhile, AI tools are predicting fair market values with 95% accuracy, reducing the guesswork in pricing. The goal? To replace the adversarial dealer-buyer dynamic with a data-driven, trust-based model.
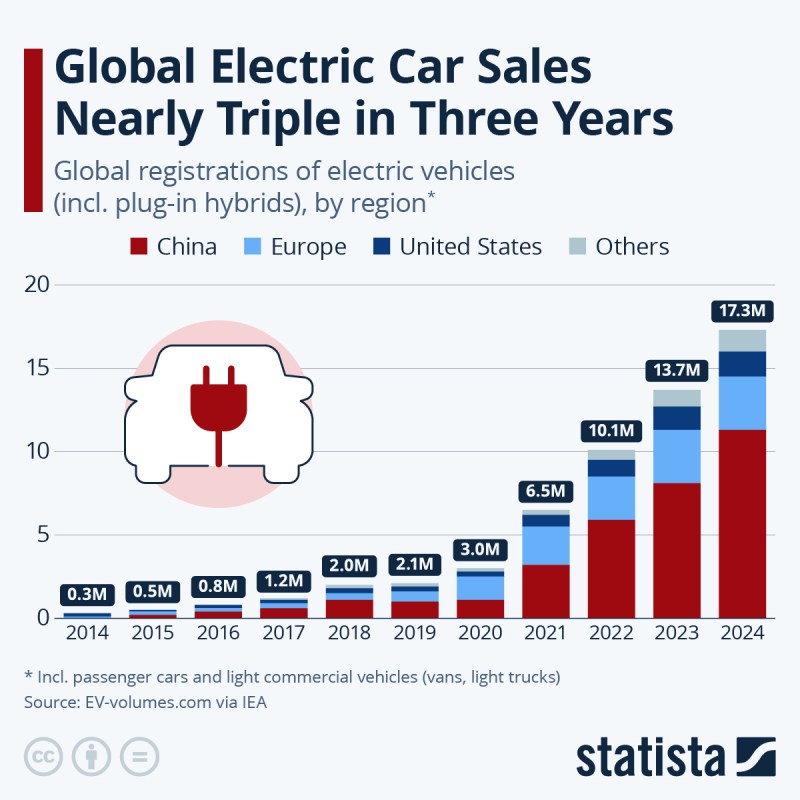
Electric vehicles (EVs) will further disrupt car sales information by introducing new variables: battery degradation data, charging infrastructure costs, and government incentives. Unlike gas cars, EVs require buyers to evaluate car sales information beyond the sticker price—think energy costs, tax credits, and even home charging setup fees. Dealers will need to adapt by offering bundled "ownership packages" that include energy plans or maintenance subscriptions. The winners in this space won’t just sell cars; they’ll sell peace of mind through car sales information clarity.
Conclusion
The gap between what dealers know and what buyers understand is the single biggest obstacle in car sales today. Closing that gap starts with treating car sales information as a non-negotiable part of the process. It’s not about outsmarting dealers—it’s about leveling the playing field. The tools exist: invoice calculators, auction data, and even dealer profit margin reports. What’s missing is the buyer’s willingness to demand them.
As the industry moves toward digital-first sales, the onus is on consumers to refuse to engage without full car sales information. Whether you’re a first-time buyer or a seasoned negotiator, the key is to approach the process with the same rigor you’d apply to a major financial investment. Because in the end, a car isn’t just a mode of transport—it’s a long-term asset. And assets, like information, are only valuable when you know their true worth.
Comprehensive FAQs
Q: How can I verify a dealer’s advertised price against the actual invoice price?
A: Use tools like Edmunds Invoice Price Calculator or Kelley Blue Book’s Dealer Cost Tool. Enter the VIN to see the dealer’s true cost, then compare it to their advertised price. For used cars, check Black Book or NADA Guides for auction sale history. If the dealer won’t disclose their invoice, walk away—they’re hiding something.
Q: Are "out-the-door" prices from online marketplaces accurate?
A: Often no. These prices typically exclude add-ons like gap insurance, undercoating, or "dealer prep" fees. Always ask for an itemized breakdown and compare it to third-party car sales information sources. TrueCar’s "Fair Purchase Price" is more reliable but still may not account for regional demand fluctuations.
Q: Can I negotiate the destination fee on a new car?
A: Rarely, but it’s worth asking. The destination fee (often $999–$1,500) is non-negotiable with most manufacturers, but some dealers may waive it if you’re financing through them or buying multiple vehicles. Check manufacturer policies—some, like Toyota, allow dealer discretion. If not, factor it into your total cost of ownership.
Q: How do I check if a used car’s price matches its market value?
A: Run the VIN through Carfax or AutoCheck for accident history, then compare the asking price to:
- Private party sales on Facebook Marketplace or Craigslist (often 5–10% below dealer prices).
- Kelley Blue Book’s Private Party Value (more accurate than retail trade-in).
- Black Book’s Used Car Values, which factor in mileage and condition.
Q: What’s the best way to avoid dealer upsells on add-ons?
A: Pre-decide which add-ons you’ll accept (e.g., only the manufacturer’s warranty) and decline the rest verbally and in writing. Dealers often bundle add-ons with the loan—if you say "no" upfront, they can’t force them. For extended warranties, buy from third parties like Endurance or CarShield for 30–50% savings. Always ask, "Is this included in the MSRP?"—if not, it’s negotiable.
Q: How do I leverage car sales information to get a better trade-in offer?
A: Start by getting a Black Book or Kelley Blue Book trade-in valuation, then use it as leverage. If the dealer lowballs, say, "I’ve seen similar vehicles trade for $X—can you match that?" Also, check local CarMax or Carvana offers, as they often pay more than dealers. Time your trade-in for the end of the month, when dealers hit sales quotas and may sweeten offers.
Q: Are there any red flags in car sales information that signal a bad deal?
A: Yes:
- Vague pricing: Dealers who won’t provide an itemized list of fees or won’t disclose their invoice price.
- High-pressure tactics: Urging you to sign before "the deal disappears" or claiming "this is our best offer."
- Unverified history: Used cars with no Carfax report or gaps in service records.
- Add-on bundles: Packaging extended warranties, paint protection, and gap insurance as a "package deal."
- Financing push: Dealers who refuse to pre-approve your loan or offer only their in-house financing (which may have hidden markups).
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of versiliasolutions.oneagency.co.