How Contractor Liability Shapes Modern Business Risks
Table of Contents
- The Complete Overview of Contractor Liability
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: What’s the difference between a contractor’s liability insurance and being named as an "additional insured"?
- Q: Can a business be held liable for a contractor’s actions if the contractor is properly classified as independent?
- Q: What happens if a contractor doesn’t have insurance, and a claim arises?
- Q: Are there industry-specific contractor liability risks I should know about?
- Q: How often should I audit my contractors’ insurance and compliance?
Every time a business hires an independent contractor—whether for construction, IT, or consulting—it enters a high-stakes game of risk transfer. A single oversight in contractor liability can expose companies to lawsuits, regulatory fines, or even bankruptcy. The problem? Many executives assume their general liability policy covers these third-party risks, only to face devastating gaps when claims arise.
Consider the case of a mid-sized firm that hired an electrician to rewire an office. When a fire broke out—later traced to faulty wiring—the contractor’s personal insurance was insufficient to cover the $2.1 million in damages. The business, despite carrying its own policy, was left footing the bill because the contractor’s liability exposure wasn’t properly addressed in the contract. This isn’t an anomaly; it’s a pattern playing out in industries from healthcare to hospitality.
The legal landscape around contractor liability has shifted dramatically in the past decade, with courts increasingly scrutinizing how businesses define "employee" versus "independent contractor" status. Misclassification alone can trigger back taxes, penalties, and lawsuits under labor laws. Meanwhile, emerging risks—like cyber threats from freelance IT workers or environmental liabilities from subcontracted trades—demand proactive strategies. The question isn’t if a business will face contractor-related liability, but how prepared it will be when it does.
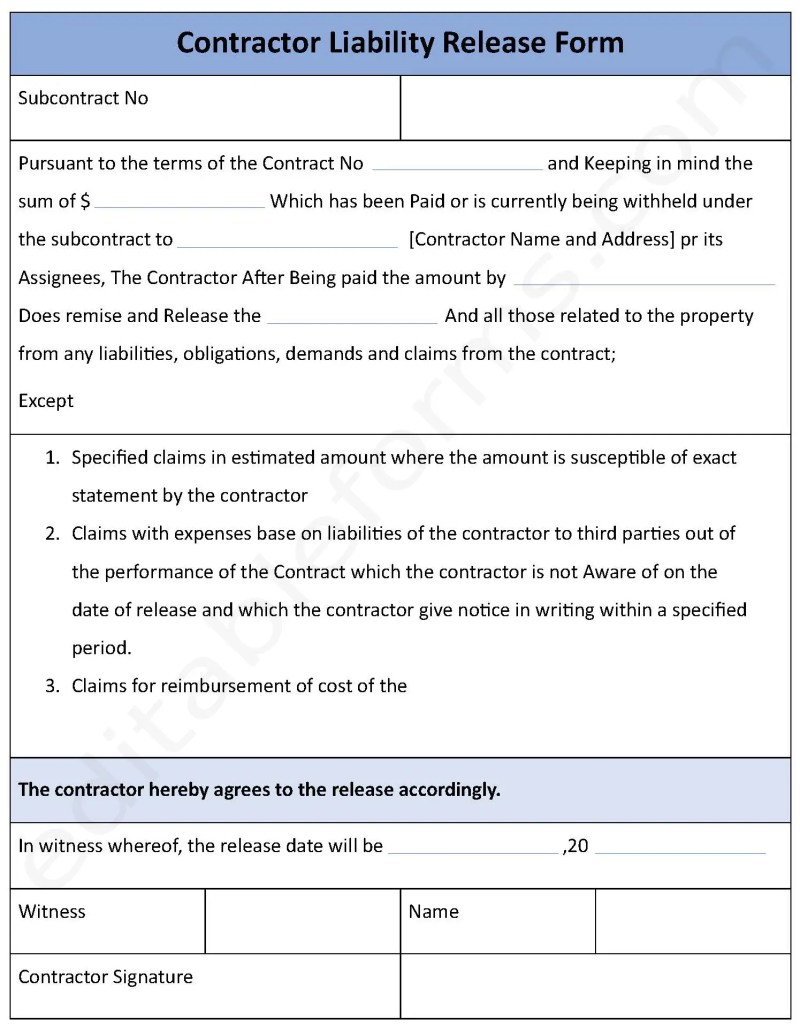
The Complete Overview of Contractor Liability
Contractor liability refers to the legal and financial responsibility a business assumes when engaging third-party professionals who operate outside its direct employment structure. Unlike traditional employee-based risks, this exposure spans contractual obligations, insurance gaps, and regulatory compliance—each with distinct consequences. The core issue? Businesses often treat contractors as cost-saving measures without accounting for the cascading risks they introduce, from property damage to professional negligence.
At its essence, contractor liability hinges on three pillars: contractual indemnification (where the contractor agrees to cover certain losses), insurance requirements (ensuring the contractor carries adequate coverage), and legal classification (avoiding misclassification as an employee). Courts and insurers increasingly demand proof that these elements are explicitly addressed, not assumed. For example, a software development firm might require contractors to maintain errors-and-omissions (E&O) insurance, but if the policy excludes certain project types, the business could still face exposure.
Historical Background and Evolution
The modern framework for contractor liability traces back to the early 20th century, when industrialization led to a surge in specialized labor. Early common law treated contractors as separate entities, but the rise of workplace injuries prompted states to introduce workers’ compensation systems—shifting liability from employers to insurers. This created a paradox: while businesses gained protection for their employees, contractors remained in legal limbo, often left to fend for themselves.
By the 1980s, the gig economy’s precursor—freelance and project-based work—exposed gaps in contractor liability coverage. Landmark cases, such as Commissioner v. Groetzinger (1989), redefined the "control test" for employee classification, forcing businesses to document contractor independence meticulously. Today, the contractor liability landscape is shaped by federal laws like the Fair Labor Standards Act (FLSA), state-specific "ABC tests," and industry-specific regulations (e.g., OSHA for construction). The evolution reflects a critical shift: businesses can no longer treat contractors as low-risk appendages but must integrate them into comprehensive risk strategies.
Core Mechanisms: How It Works
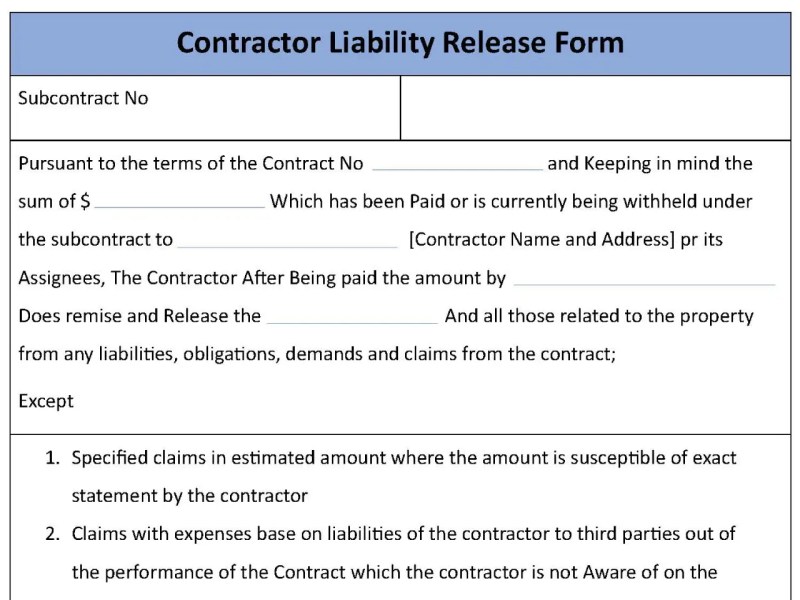
The mechanics of contractor liability operate through a combination of pre-engagement safeguards and post-incident recourse. Before hiring, businesses must verify the contractor’s certifications, insurance certificates (COIs), and financial stability. For instance, a general contractor might require subcontractors to provide proof of liability insurance with limits matching the project’s risk profile. During the engagement, contractual clauses—such as hold harmless agreements or additional insured endorsements—transfer risk back to the contractor where possible.
When incidents occur, the process becomes a legal chess match. If a contractor’s negligence causes harm, the business’s first line of defense is its own general liability policy. However, if the contractor’s insurance is insufficient or denies the claim, the business may face a subrogation claim from its insurer, demanding reimbursement. This is why many high-risk industries—like healthcare or energy—mandate umbrella policies for contractors, ensuring coverage extends beyond standard limits. The key takeaway: contractor liability isn’t just about insurance; it’s about documentation, communication, and proactive risk allocation.
Key Benefits and Crucial Impact
Proactively managing contractor liability isn’t just a legal checkbox—it’s a competitive advantage. Businesses that treat contractors as extensions of their risk framework gain access to specialized talent without sacrificing financial stability. For example, a retail chain that requires all store remodel contractors to carry commercial general liability with $2 million in coverage avoids the nightmare of a single lawsuit derailing its expansion plans. The impact extends beyond finances: companies with robust contractor liability protocols often secure better terms with suppliers, landlords, and even customers who prioritize risk-mitigated partnerships.
Yet the benefits are asymmetric. A 2023 study by the Risk & Insurance Management Society found that 68% of businesses with contractor-related claims lacked proper documentation to shift liability back to the contractor. This lack of preparation leads to prolonged disputes, higher legal fees, and reputational damage. The stakes are highest in sectors like construction, where a single contractor liability oversight can trigger OSHA fines, project delays, or even criminal charges for unsafe conditions. The message is clear: contractor liability isn’t an optional layer of protection—it’s the foundation of resilient business operations.
"The most common mistake businesses make isn’t hiring unqualified contractors—it’s assuming their insurance will cover the contractor’s mistakes. By the time a claim arises, it’s often too late to negotiate."
— David Reynolds, Partner at Reed Smith LLP
Major Advantages
- Financial Protection: Proper contractor liability clauses and insurance requirements prevent businesses from absorbing costs for third-party negligence, such as property damage or bodily injury.
- Regulatory Compliance: Adhering to contractor liability standards (e.g., FLSA classification, state ABC tests) avoids costly misclassification penalties, which can exceed $25,000 per violation under federal law.
- Insurance Cost Efficiency: Insurers offer discounts to businesses that enforce contractor liability protocols, as they demonstrate lower risk profiles. For example, a construction firm with strict contractor insurance mandates may see a 15–20% reduction in premiums.
- Operational Continuity: Clear contractor liability agreements minimize disputes during projects, reducing delays and preserving vendor relationships.
- Reputational Safeguarding: High-profile contractor liability failures (e.g., a data breach caused by a freelance IT contractor) can erode customer trust. Proactive management signals reliability to clients and partners.
Comparative Analysis
| Aspect | Employee Liability | Contractor Liability |
|---|---|---|
| Legal Classification | Covered under workers’ comp and unemployment insurance; employer bears primary liability. | Determined by IRS/state tests (e.g., "ABC test"); contractor bears primary liability unless misclassified. |
| Insurance Requirements | Employer’s policy (e.g., workers’ comp) typically covers workplace injuries. | Contractor must provide liability insurance (e.g., CGL, E&O) with specified limits; business may require additional insured status. |
| Risk Transfer Tools | Limited to internal policies and OSHA compliance. | Contractual indemnification, hold harmless clauses, and insurance endorsements (e.g., "additional insured" endorsements). |
| Compliance Costs | Higher due to payroll taxes, benefits, and workers’ comp premiums. | Lower upfront, but higher if contractor liability gaps lead to lawsuits or fines. |
Future Trends and Innovations
The next frontier in contractor liability management lies in predictive analytics and blockchain-based verification. Insurtech firms are already deploying AI to assess contractor risk profiles in real time, flagging red flags like past claims or financial instability before a contract is signed. Meanwhile, blockchain is being tested to create tamper-proof records of insurance certificates and project documentation, reducing the "he said, she said" disputes that plague contractor liability claims. These innovations will force businesses to adopt dynamic risk frameworks—where contractor liability isn’t static but evolves with each project’s risk profile.
Regulatory pressure will also reshape contractor liability. The Biden administration’s push for stricter independent contractor classification rules (expected in 2024) could redefine who qualifies as a contractor versus an employee, tightening the screws on businesses that rely on gig workers. Simultaneously, states like California and New York are expanding joint employer liability laws, making it easier for plaintiffs to hold businesses accountable for contractors’ actions. The result? A more litigious environment where contractor liability strategies must be both defensive and proactive.
Conclusion
The myth that contractors are "low-risk" is exactly that—a myth. The reality is that contractor liability is one of the most underappreciated yet high-impact risks businesses face today. The companies that thrive in this landscape are those that treat contractor liability as an integral part of their risk management ecosystem, not an afterthought. This means moving beyond generic insurance requirements to customized, project-specific safeguards, from AI-driven risk assessments to ironclad contractual language.
As the legal and technological landscapes evolve, the businesses that fail to adapt will pay the price—not just in dollars, but in lost opportunities and damaged reputations. The time to act is now, before a single oversight turns a contractor into a liability nightmare. The question isn’t whether your business can afford to ignore contractor liability—it’s whether it can afford the consequences of doing so.
Comprehensive FAQs
Q: What’s the difference between a contractor’s liability insurance and being named as an "additional insured"?
A: A contractor’s liability insurance (e.g., commercial general liability) covers their own negligence, but it won’t automatically protect your business unless you’re listed as an additional insured. Without this endorsement, your business could still face claims if the contractor’s policy denies coverage or has insufficient limits. Always verify the endorsement type—some only apply to specific claims (e.g., "occurrence-based" vs. "claims-made" policies).
Q: Can a business be held liable for a contractor’s actions if the contractor is properly classified as independent?
A: Yes. Even with proper classification, businesses can face contractor liability under vicarious liability theories if they exert significant control over the work (e.g., dictating hours, tools, or project details). Courts may also apply joint employer liability if the contractor’s actions directly benefit the business (e.g., a freelance salesperson causing harm). The safest approach is to document the contractor’s independence in writing and avoid overlapping responsibilities with employees.
Q: What happens if a contractor doesn’t have insurance, and a claim arises?
A: If a contractor lacks liability insurance, your business’s general liability policy may cover the claim—but only up to its limits. Your insurer will then pursue the contractor for reimbursement (a process called subrogation). If the contractor is insolvent, you’re left holding the bill. To mitigate this, require certificates of insurance (COIs) upfront and include liquidated damages clauses in contracts for non-compliance.
Q: Are there industry-specific contractor liability risks I should know about?
A: Absolutely. For example:
- Construction: OSHA violations by contractors can trigger fines up to $156,259 per serious violation, plus contractor liability for unsafe conditions.
- Healthcare: HIPAA violations by contractor IT staff can lead to $1.5 million+ fines if patient data is exposed.
- Tech: Cybersecurity breaches caused by freelance developers may void your cyber insurance if the contractor wasn’t vetted.
- Retail: Product liability claims from third-party vendors (e.g., dropshippers) can implicate your business if contracts lack indemnification clauses.
Q: How often should I audit my contractors’ insurance and compliance?
A: At a minimum, conduct annual audits of all active contractors’ insurance certificates (COIs) and compliance documentation. High-risk industries (e.g., construction, healthcare) should perform quarterly spot checks, especially for contractors handling sensitive work (e.g., asbestos removal, patient data). Automated tools like Insurance Verification Services (IVS) can streamline this process by flagging lapses or policy changes in real time.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of versiliasolutions.oneagency.co.