How Event Insurance Coverage Protects Your Biggest Investments
Table of Contents
- The Complete Overview of Event Insurance Coverage
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: What’s the difference between event cancellation insurance and liability insurance?
- Q: Can I get event insurance coverage for a last-minute event?
- Q: Does event insurance cover COVID-19 or other pandemics?
- Q: What’s the average cost of event insurance coverage?
- Q: What should I do if my event insurance claim is denied?
- Q: Do I need event insurance if my venue already has coverage?
- Q: Can I insure a virtual event?
Hosting an event—whether a multimillion-dollar corporate gala or a once-in-a-lifetime wedding—is a high-stakes endeavor. One unexpected disaster—a hurricane, a vendor default, or a food poisoning outbreak—can turn months of meticulous planning into a financial nightmare. Yet, many organizers still treat event insurance coverage as an afterthought, assuming "it’ll never happen to me." The reality? The U.S. alone sees over $10 billion in event-related losses annually, with cancellations and liability claims accounting for the bulk. Without proper event insurance coverage, a single incident can wipe out budgets, damage reputations, and leave organizers personally liable for damages.
The stakes are even higher for large-scale productions. Take the 2021 Coachella cancellation due to COVID-19—organizers faced $200 million in losses, a fraction of which was recouped through insurance. Meanwhile, a 2022 study by the Event Safety Alliance found that 68% of insured events recovered 70-100% of their losses, while uninsured events saw 90% of organizers declare bankruptcy or file lawsuits to recover costs. The data is clear: Event insurance coverage isn’t just a safety net—it’s a financial lifeline.
Yet, the industry remains fragmented. Policies vary wildly by provider, event type, and geographic risk factors. A wedding planner in Florida might need hurricane-specific endorsements, while a tech conference in Silicon Valley requires cyber-liability riders. The lack of standardization means organizers often overpay for redundant coverage or, worse, leave critical gaps exposed. This guide cuts through the noise to explain how event insurance coverage functions, its often-overlooked advantages, and how to tailor a policy to your event’s unique risks—before disaster strikes.

The Complete Overview of Event Insurance Coverage
Event insurance coverage is a specialized risk management tool designed to mitigate financial losses from cancellations, interruptions, property damage, or third-party liabilities. Unlike general liability insurance, which covers broad risks, event insurance coverage is customizable, addressing everything from vendor non-performance to terrorism-related disruptions. The market has evolved from niche offerings in the 1980s—when policies were primarily tied to high-profile concerts—to a $5 billion global industry, now encompassing everything from backyard barbecues to Super Bowl halftime shows.The complexity lies in the modular nature of policies. A standard event cancellation insurance policy might cover weather-related postponements, but adding a "contingency clause" for pandemics could double the premium. Meanwhile, liability insurance for events often includes general aggregate limits (e.g., $1 million per occurrence) but may exclude alcohol-related incidents unless specified. The key to effective event insurance coverage is aligning the policy with the event’s risk profile, not just checking boxes on a broker’s form.
Historical Background and Evolution
The origins of event insurance coverage trace back to the 1960s, when large-scale music festivals like Woodstock faced logistical nightmares—from rain-soaked attendees to last-minute permits. Early policies were reactive, designed to cover losses after disasters occurred. However, the 1980s saw a shift as corporate retreats and trade shows became targets for terrorist threats (e.g., the 1986 Achille Lauro hijacking), prompting insurers to introduce political violence riders. By the 2000s, the rise of destination weddings and luxury yacht parties created demand for marine-specific endorsements and international medical evacuation coverage.The COVID-19 pandemic acted as a catalyst, exposing critical gaps in traditional event insurance coverage. Many policies excluded pandemics as "known events," leaving organizers like the 2020 Tokyo Olympics scrambling to renegotiate contracts. In response, insurers now offer "force majeure" add-ons, which cover unforeseeable disruptions—though these come with stricter definitions of "force majeure." The evolution reflects a broader trend: event insurance coverage is no longer a static product but a dynamic risk-transfer mechanism adapting to global instability.
Core Mechanisms: How It Works
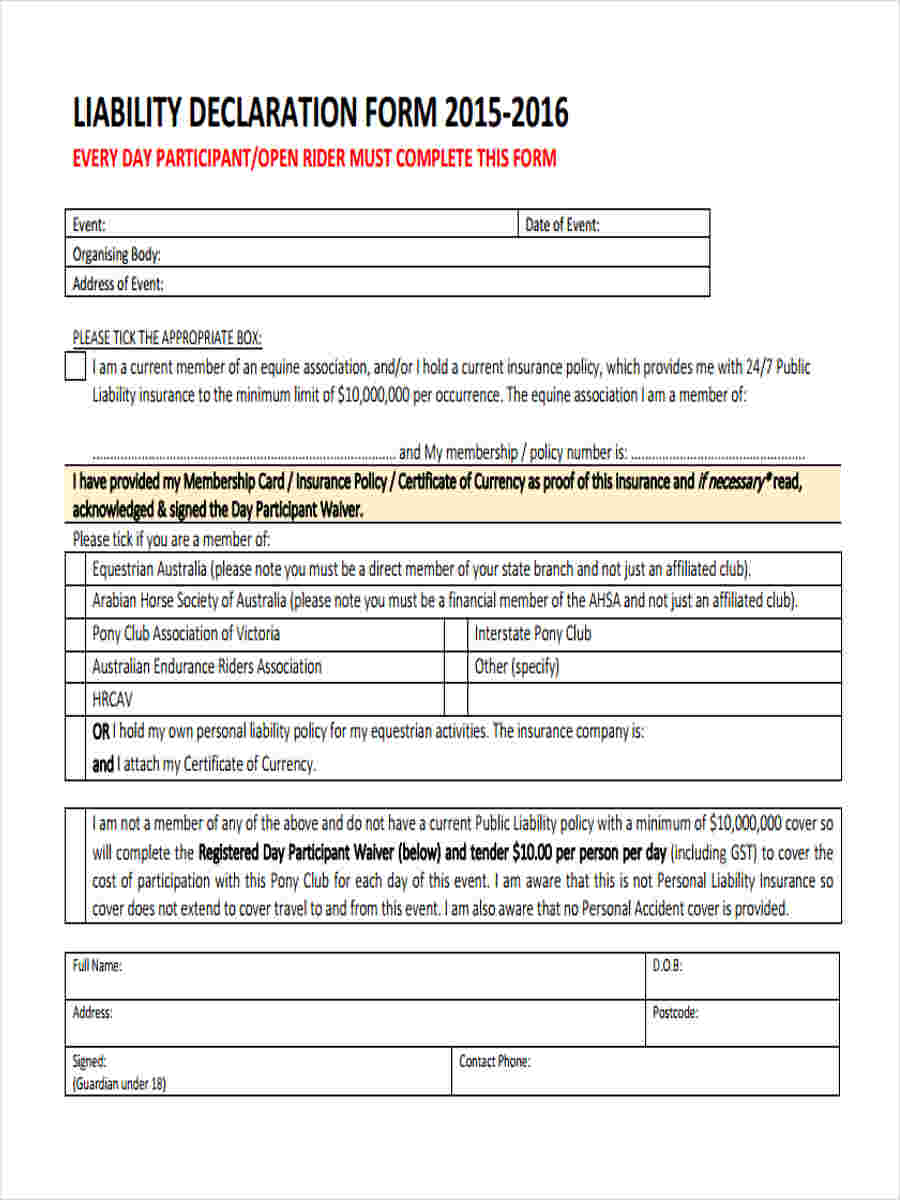
At its core, event insurance coverage operates on a loss-sharing model. The insurer agrees to reimburse the policyholder for covered losses up to the policy limits, minus a deductible (typically 5-15% of the insured amount). For example, if a $500,000 wedding is insured for $400,000 with a 10% deductible, the insurer would pay $360,000 for a hurricane cancellation, leaving the client responsible for $40,000. The claim process begins with pre-loss documentation, including contracts, vendor agreements, and weather forecasts—delays here can void coverage.The policy’s trigger conditions are critical. A cancellation policy might activate if the event is postponed or canceled due to named perils (e.g., fire, flood, death of a key attendee). Meanwhile, liability coverage kicks in if a guest slips on ice or a pyrotechnics display malfunctions. The declaration page—a one-page summary of coverage—is where most disputes arise. A common oversight? Exclusions for "willful misconduct"—meaning if an organizer knowingly misrepresents risks, the claim is denied. Understanding these mechanics is essential to avoiding denied claims, which cost the industry $1.2 billion annually.
Key Benefits and Crucial Impact
The primary value of event insurance coverage lies in financial protection, but its secondary benefits—vendor confidence, legal safeguards, and reputational shielding—often go unnoticed. Without insurance, vendors may refuse to work without payment upfront, and venues might deny permits if the organizer lacks liability proof. Even a single lawsuit from an injured attendee can bankrupt a small business; event insurance coverage ensures legal defense costs are covered. The peace of mind factor is equally critical—organizers can focus on execution rather than worrying about worst-case scenarios.Insurance also levels the playing field in negotiations. A corporate client hosting a conference can insist on vendor performance bonds (a type of event insurance coverage) to guarantee caterers and AV teams deliver. Similarly, wedding planners with liability insurance can secure higher-end venues that require proof of coverage. The hidden cost of self-insuring—the time spent managing risks instead of growing the business—often outweighs the premium expenses.
"Event insurance isn’t about predicting the future—it’s about preparing for the unpredictable. The events that survive are those that treat insurance as a strategic investment, not an optional expense." — Mark Johnson, CEO of EventRisk Solutions
Major Advantages
- Financial Recovery: Reimburses non-refundable deposits (hotels, venues) and vendor costs if the event is canceled or interrupted. Without coverage, organizers often lose 80-90% of pre-paid expenses.
- Vendor Assurance: Many high-end vendors require proof of insurance before signing contracts. Policies with vendor default clauses can even cover last-minute replacements if a key supplier fails.
- Liability Shield: Covers medical expenses, property damage, and legal fees if an attendee is injured or a third party sues. A single slip-and-fall claim can cost $50,000+—insurance caps exposure at the policy limit.
- Contingency Planning: Policies often include alternative date coverage, allowing organizers to reschedule without losing deposits (e.g., if a venue becomes unavailable).
- Tax and Contract Benefits: Some jurisdictions allow insurance premiums to be deducted as a business expense. Additionally, insured events can negotiate better terms with venues (e.g., waived fees for insurance-backed guarantees).
Comparative Analysis
| Standard Event Cancellation Insurance | Specialized Event Liability Insurance |
|---|---|
|
|
| Cyber Liability Insurance for Events | Marine/Transportation Event Insurance |
|
|
Future Trends and Innovations
The next decade of event insurance coverage will be shaped by AI-driven risk assessment and parametric triggers. Insurers are already using machine learning to predict cancellation risks by analyzing historical weather data, vendor credit scores, and geopolitical instability. For example, a policy might automatically pay out if a hurricane enters a 50-mile radius—eliminating the need for manual claims. Blockchain-based smart contracts could further streamline payouts, reducing fraud and speeding up reimbursements.Another emerging trend is micro-insurance for events, where organizers buy short-term, pay-as-you-go coverage for high-risk elements (e.g., one-day festival insurance). Meanwhile, climate-specific policies are gaining traction, with wildfire endorsements in California and flood exclusions in Louisiana becoming standard. The post-pandemic shift toward hybrid events has also spurred demand for virtual event insurance, covering tech failures, Zoom hacking, and digital attendee disputes.
Conclusion
Event insurance coverage is no longer optional—it’s a non-negotiable component of modern event planning. The organizations that thrive are those that treat risk management as seriously as guest lists and decor. Yet, the industry’s complexity means one-size-fits-all policies rarely suffice. The key is customization: pairing cancellation insurance with liability riders, vendor performance bonds, and climate-specific add-ons to create a tailored safety net.The cost of skipping coverage is far higher than the premium. A single avoidable loss can erase years of revenue, while insured events recover 80% of their value on average. As global risks evolve—from cyberattacks to climate disasters—the events that survive will be those that proactively mitigate threats. The message is clear: Event insurance coverage isn’t an expense—it’s the foundation of resilience.
Comprehensive FAQs
Q: What’s the difference between event cancellation insurance and liability insurance?
A: Event cancellation insurance reimburses financial losses if the event is postponed or canceled (e.g., due to weather, vendor failure). Liability insurance covers third-party claims (e.g., injuries, property damage). Many policies bundle both, but they serve distinct purposes—cancellation protects your budget, while liability protects your assets and reputation.
Q: Can I get event insurance coverage for a last-minute event?
A: Some insurers offer short-term policies (as little as 48 hours before the event), but coverage limits and exclusions may be stricter. Ideal timing is 30-90 days out, allowing underwriters to assess risks. For immediate needs, consider umbrella liability policies or vendor-supplied coverage (e.g., venue-provided insurance).
Q: Does event insurance cover COVID-19 or other pandemics?
A: Most standard policies exclude pandemics as "known events." However, specialized add-ons (e.g., "force majeure" riders) can cover government-mandated cancellations. Always confirm with your broker—some insurers now offer pandemic-specific endorsements for an extra premium.
Q: What’s the average cost of event insurance coverage?
A: Premiums vary widely:
- Weddings: $300–$1,500 (depending on guest count and location).
- Corporate Events: 1–3% of total event cost.
- Festivals/Concerts: $5,000–$50,000+ (based on attendance and risk factors).
Q: What should I do if my event insurance claim is denied?
A: First, review the denial letter—most cite exclusions, late filings, or missing documentation. Common reasons for denial:
- Failure to mitigate losses (e.g., not seeking alternative vendors).
- Misrepresented risks (e.g., hiding a high-risk activity).
- Late notice (most policies require claims within 30–90 days).
Q: Do I need event insurance if my venue already has coverage?
A: Venue insurance typically covers property damage and basic liability, but it does not protect your event’s unique risks. For example:
- A venue policy won’t reimburse your non-refundable vendor deposits if you cancel.
- It may exclude your event’s specific activities (e.g., a live cooking demo with fire risks).
- Personal liability (e.g., a guest suing you directly) is often not covered by the venue.
Q: Can I insure a virtual event?
A: Yes, virtual event insurance is growing in demand. Policies typically cover:
- Tech failures (e.g., platform crashes during a keynote).
- Cyber liability (e.g., attendee data breaches).
- Zoom bombing/hacking incidents.
- Refunds for no-shows (if the event is unwatchable due to technical issues).
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of versiliasolutions.oneagency.co.