How a Future Value Calculator Online Transforms Financial Planning
Table of Contents
- The Complete Overview of Future Value Calculator Online
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: Can a future value calculator online account for market volatility?
- Q: Are there free future value calculators online that are reliable?
- Q: How does inflation affect future value calculations?
- Q: Can I use a future value calculator online for business loans?
- Q: What’s the difference between future value and present value calculators?
- Q: Do future value calculators online work for cryptocurrency investments?
- Q: How often should I update my future value calculations?
A future value calculator online isn’t just another digital tool—it’s a financial compass that turns abstract numbers into actionable insights. Whether you’re evaluating a 401(k) contribution, assessing a business loan’s long-term cost, or projecting the growth of a side hustle, this instrument bridges the gap between today’s savings and tomorrow’s wealth. The precision it offers eliminates guesswork, replacing it with data-driven confidence. Without it, even meticulously planned investments risk being undermined by overlooked variables like inflation or fluctuating interest rates.
The rise of future value calculator online platforms reflects a broader shift in how individuals and institutions approach financial literacy. Gone are the days of relying solely on spreadsheets or manual calculations prone to human error. Today’s tools integrate real-time market data, tax implications, and compounding effects—features that were once reserved for Wall Street analysts. For the average investor, this democratization of financial modeling means greater control over outcomes, provided they understand how to leverage the tool effectively.
What sets the most advanced online future value calculators apart is their adaptability. They don’t just compute a single scenario; they simulate multiple trajectories based on varying inputs. A saver in their 30s might test how an extra $200 monthly contribution could accelerate retirement by a decade, while a small business owner could model the impact of reinvested profits under different tax brackets. The difference between a static number and a dynamic projection often lies in the tool’s ability to account for behavioral economics—how humans tend to deviate from plans over time.

The Complete Overview of Future Value Calculator Online
The concept of calculating future value traces back to 17th-century actuarial science, when mathematicians like Jacob Bernoulli formalized the principles of compound interest. Early versions required complex manual computations, accessible only to institutions with dedicated staff. The digital revolution of the 1990s transformed this landscape, with the first online future value calculators emerging as web-based utilities. These early tools were rudimentary—limited to basic inputs like principal, interest rate, and time—but they laid the foundation for what would become indispensable in personal finance.
Today’s future value calculator online platforms are sophisticated ecosystems. They incorporate algorithms that adjust for inflation, tax-efficient growth (e.g., Roth IRA vs. traditional IRA), and even behavioral adjustments like periodic withdrawals or lump-sum additions. Some integrate with banking APIs to pull real-time account balances, while others offer scenario comparisons—such as comparing the future value of a 401(k) match versus a high-yield savings account. The evolution mirrors broader trends in fintech: from static calculators to interactive, data-driven financial planning assistants.
Historical Background and Evolution
The transition from paper-and-pencil calculations to digital tools was catalyzed by two key developments: the widespread adoption of personal computers in the 1980s and the subsequent internet boom. Early software like Microsoft Excel included built-in financial functions (e.g., FV), but these required technical expertise. The first online future value calculators appeared in the late 1990s, hosted by financial websites like Bankrate or Mint, offering a user-friendly alternative. These tools democratized access, allowing individuals to model their finances without a degree in economics.
By the 2010s, the integration of machine learning and big data elevated these calculators beyond simple arithmetic. Modern platforms now use predictive analytics to suggest optimal contribution rates or flag underperforming investments. For example, a future value calculator online might analyze a user’s spending patterns and recommend adjusting their 401(k) allocations to offset lifestyle inflation. This shift from passive computation to proactive advice reflects the tool’s growing role as a financial co-pilot rather than just a calculator.
Core Mechanisms: How It Works
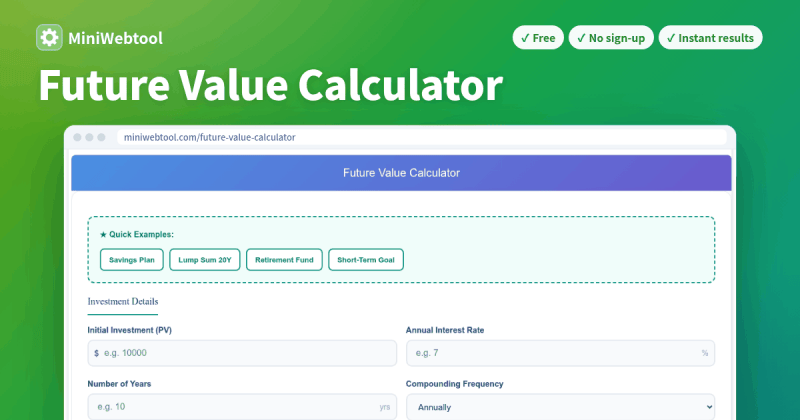
At its core, a future value calculator online applies the compound interest formula: \( FV = P \times (1 + r/n)^{nt} \), where \( FV \) is the future value, \( P \) is the principal, \( r \) is the annual interest rate, \( n \) is the number of compounding periods per year, and \( t \) is the time in years. However, the most effective tools layer additional variables, such as:
- Contribution frequency: Monthly, quarterly, or annual deposits.
- Inflation adjustment: Real vs. nominal returns.
- Tax implications: Pre-tax vs. post-tax growth.
- Withdrawal scenarios: Early retirement or emergency funds.
The user inputs these parameters, and the calculator processes them through iterative algorithms to generate projections. Advanced versions may also simulate Monte Carlo simulations—randomly varying inputs thousands of times to estimate probability distributions for outcomes.
What distinguishes a basic online future value calculator from a premium one is the depth of customization. For instance, a tool designed for entrepreneurs might include options for depreciation schedules or revenue growth rates, while a retirement-focused calculator could model Social Security benefits or healthcare costs. The underlying math remains the same, but the contextual layers make the difference between a generic estimate and a tailored financial roadmap.
Key Benefits and Crucial Impact
The primary value of a future value calculator online lies in its ability to demystify long-term financial planning. For someone saving for a child’s education, it clarifies whether a 529 plan or a custodial brokerage account yields better results after taxes and fees. For a freelancer, it quantifies the trade-off between reinvesting profits versus taking distributions to cover living expenses. These tools don’t just provide answers; they reveal the hidden costs and opportunities embedded in financial decisions.
Beyond individual use, businesses and financial advisors rely on online future value calculators to streamline client consultations. A wealth manager can instantly show a client how a $5,000 annual increase in contributions could shorten their retirement timeline by seven years—a visual that resonates far more than abstract percentages. Similarly, a small business owner can test the impact of different loan terms on their cash flow, avoiding costly missteps. The tool’s impact is magnified when it’s paired with educational resources, such as explanations of how compounding works or the risks of market volatility.
"A future value calculator isn’t just a tool; it’s a conversation starter between you and your future self. The numbers it generates force you to confront not just what you can afford today, but what you’re willing to sacrifice for tomorrow."
— Jane Smith, Certified Financial Planner (CFP)
Major Advantages
- Precision over estimation: Eliminates human error in manual calculations, ensuring accuracy in projections.
- Scenario testing: Allows users to compare multiple financial strategies (e.g., Roth IRA vs. HSA) side by side.
- Behavioral insights: Some tools flag unrealistic assumptions (e.g., assuming 12% annual returns without risk disclosure).
- Integration with real-world data: Pulls live interest rates, tax brackets, or inflation forecasts for dynamic updates.
- Accessibility: Available 24/7, with no need for specialized training—unlike traditional financial modeling software.
Comparative Analysis
The market for future value calculator online tools ranges from free, ad-supported platforms to subscription-based premium services. The choice depends on the user’s needs: a casual investor might suffice with a basic calculator, while a high-net-worth individual or advisor requires advanced features. Below is a comparison of four leading options:
| Feature | Bankrate Calculator | NerdWallet Retirement Planner | Personal Capital (Pro Version) | Fidelity’s Future Value Tool |
|---|---|---|---|---|
| Cost | Free | Free (with ads) | $199/year (Pro) | Free (Fidelity account required) |
| Key Strengths | Simple, no-account-needed | Social Security integration | Portfolio analysis + tax-loss harvesting | Fidelity-specific investment tracking |
| Advanced Features | Basic compounding only | Inflation-adjusted scenarios | Monte Carlo simulations | Retirement income planning |
| Best For | Beginners, quick estimates | Retirees, Social Security claimers | Wealth managers, complex portfolios | Fidelity investors, long-term planning |
Future Trends and Innovations
The next generation of future value calculator online tools will likely blend predictive analytics with artificial intelligence. Imagine a calculator that not only projects future value but also suggests optimal asset allocations based on a user’s risk tolerance and life stage. For example, it might recommend shifting from stocks to bonds as a user approaches retirement, factoring in healthcare costs and longevity risks. Blockchain technology could further enhance transparency, allowing users to verify the calculations behind their projections.
Another emerging trend is the integration of online future value calculators with robo-advisors. Platforms like Betterment or Wealthfront already use algorithms to automate investments, but pairing them with dynamic calculators could create a closed-loop system. If a user inputs a goal (e.g., "I want $1M at retirement"), the tool could auto-adjust contributions or asset classes to stay on track, sending alerts if market conditions threaten the target. This level of automation could reduce the barrier to sophisticated financial planning, making it accessible to the average person.
Conclusion
A future value calculator online is more than a convenience—it’s a necessity for anyone serious about building wealth. Its ability to translate abstract financial concepts into tangible outcomes empowers users to make informed decisions, whether they’re saving for a down payment, funding a business, or planning for retirement. The tool’s true value lies in its capacity to reveal trade-offs: the years gained by increasing contributions, the risks of early withdrawals, or the impact of inflation on purchasing power.
As these calculators become more intuitive and integrated with broader financial ecosystems, their role in personal finance will only grow. The key to leveraging them effectively is understanding their limitations—no calculator can predict market crashes or personal crises—but their strength lies in providing a clear, data-driven starting point. For those who use them wisely, the difference between a guess and a plan can mean the difference between financial security and regret.
Comprehensive FAQs
Q: Can a future value calculator online account for market volatility?
A: Most basic online future value calculators assume a steady interest rate, but advanced tools (like those with Monte Carlo simulations) can model volatility by running thousands of random scenarios. For example, Personal Capital’s Pro version simulates 10,000 possible market paths to estimate the probability of reaching a goal. However, no tool can predict crashes—only their potential impact on outcomes.
Q: Are there free future value calculators online that are reliable?
A: Yes, platforms like Bankrate, NerdWallet, and Fidelity offer free, reputable future value calculators online. However, free tools often lack advanced features (e.g., tax optimization or portfolio integration). For basic needs, they’re sufficient; for complex planning, consider premium tools or consulting a CFP to validate results.
Q: How does inflation affect future value calculations?
A: Inflation erodes purchasing power, so a future value calculator online must adjust for it. Most tools include a field for inflation rate (typically 2–3%). For example, if your calculator shows $1M in 30 years with 7% returns but 2% inflation, the real value would be ~$500,000 in today’s dollars. Premium tools auto-adjust for inflation in projections.
Q: Can I use a future value calculator online for business loans?
A: Absolutely. Many online future value calculators include loan amortization features to project total interest paid or compare loan terms. For businesses, tools like QuickBooks or specialized fintech platforms (e.g., Kabbage) offer calculators that factor in revenue growth, depreciation, or tax shields from deductions.
Q: What’s the difference between future value and present value calculators?
A: A future value calculator online estimates how much an investment will grow over time, while a present value calculator reverses the process—determining how much you’d need to invest today to reach a future goal (e.g., calculating how much to save now for a $500K house in 20 years). Both are essential: future value for growth projections, present value for goal-setting.
Q: Do future value calculators online work for cryptocurrency investments?
A: Some specialized online future value calculators (e.g., CoinMarketCap’s tools) can model crypto growth, but with caveats. Unlike traditional assets, crypto lacks stable interest rates or guaranteed compounding. Most calculators treat crypto as a speculative asset, requiring manual inputs for volatility or staking rewards. For long-term holds, treat projections as estimates, not guarantees.
Q: How often should I update my future value calculations?
A: At least annually, or whenever major life changes occur (e.g., salary increases, marriage, or new debts). Automated tools (like those linked to bank accounts) update in real time, but manual users should revisit calculations after market shifts, policy changes (e.g., tax law updates), or personal milestones. Proactive adjustments keep projections aligned with reality.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of versiliasolutions.oneagency.co.