How the Instant Money App Revolutionizes Finance in 2024
Table of Contents
- The Complete Overview of Instant Money Apps
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: Are instant money apps safe to use?
- Q: Can I use an instant money app for international transfers?
- Q: Do instant money apps affect my credit score?
- Q: What happens if I send money to the wrong recipient?
- Q: Are there limits on how much I can send instantly?
- Q: Can I get my money back if the app shuts down?
The global shift toward digital transactions has made instant money apps indispensable. These platforms eliminate waiting periods, replacing traditional banking delays with real-time fund transfers. For businesses and individuals alike, the ability to access cash instantly—whether for emergencies, purchases, or investments—has redefined financial agility.
Yet, not all instant money apps are created equal. Some prioritize speed over security, while others balance convenience with regulatory compliance. The rise of these services reflects broader economic trends: a demand for frictionless transactions in an era where time is currency. Understanding their mechanics, risks, and future potential is critical for anyone navigating modern finance.
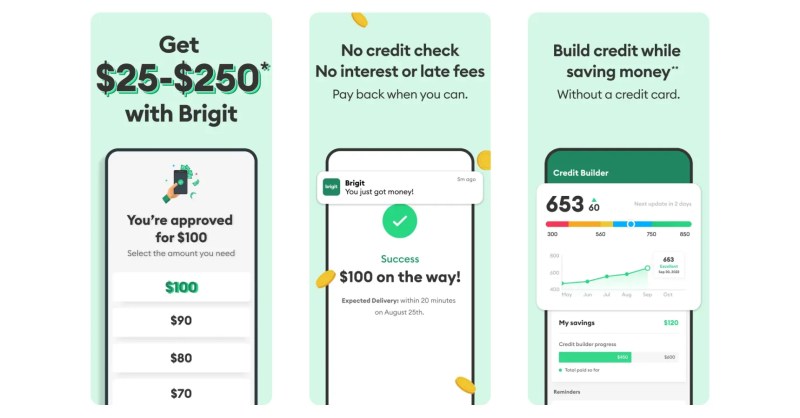
The Complete Overview of Instant Money Apps
Instant money apps leverage fintech infrastructure to process transactions within seconds, often via bank linkages, digital wallets, or peer-to-peer networks. Unlike traditional banking systems that rely on clearing cycles, these platforms use APIs, blockchain (in some cases), and real-time settlement systems to execute transfers instantly. Their popularity stems from addressing a fundamental pain point: the need for immediate liquidity without physical cash or prolonged waits.The ecosystem of instant money apps spans consumer-focused tools like Cash App and Venmo to B2B solutions such as Wise or Revolut. Each serves distinct niches—whether for microtransactions, cross-border payments, or merchant settlements. However, their growth has also sparked debates about financial inclusion, fraud risks, and the erosion of traditional banking’s role in the economy.
Historical Background and Evolution
The concept of instant money transfers traces back to the 1990s with early online banking experiments, but it was the 2010s that saw explosive innovation. Mobile payment systems like M-Pesa in Kenya demonstrated that real-time transactions could thrive in underserved markets. Meanwhile, Western fintechs began integrating instant payment rails (e.g., FedNow in the U.S. or SEPA Instant in Europe) to compete with cash-based economies.Today, instant money apps are no longer niche—they’re mainstream. The COVID-19 pandemic accelerated adoption, as contactless payments and digital wallets became essential. Regulators have responded with frameworks like PSD2 in Europe, mandating open banking standards that enable faster, secure transactions. This evolution underscores a shift from reactive finance (waiting for funds) to proactive, on-demand access.
Core Mechanisms: How It Works
At their core, instant money apps rely on three key components: instant payment networks, identity verification, and liquidity pooling. For example, when a user requests a transfer via an app like PayPal or Chime, the system checks the sender’s account balance in real time, verifies the recipient’s details (often via biometric authentication), and routes the funds through a high-speed clearing network. Blockchain-based apps (e.g., Ripple) use decentralized ledgers to settle transactions in under 4 seconds.Security is enforced through encryption, tokenization, and fraud detection algorithms. Some apps also employ "hold periods" for large transactions to mitigate risks, though this slightly delays the "instant" promise. The trade-off between speed and security remains a defining challenge for developers.
Key Benefits and Crucial Impact
Instant money apps address a fundamental human need: immediate access to funds. For gig workers, this means receiving payments without daily delays; for retailers, it reduces cash flow gaps. The psychological impact is equally significant—reducing financial stress by eliminating uncertainty about when money will arrive. Businesses, in particular, benefit from streamlined payroll and vendor settlements, cutting operational costs.Yet, the broader implications extend to economic equity. In regions with limited banking infrastructure, instant money apps provide financial inclusion, allowing unbanked populations to participate in the digital economy. Critics, however, warn of potential over-reliance on these tools, which may exacerbate debt cycles or enable illicit activities if unchecked.
"The future of money is not about physical notes but about seamless, instant transactions that adapt to human behavior—not the other way around." — Satya Nadella, Microsoft CEO (2023 Fintech Summit)
Major Advantages
- Speed: Transactions complete in seconds, unlike traditional bank transfers (1–3 business days). Ideal for time-sensitive needs like medical bills or travel bookings.
- Accessibility: No branch visits required; apps operate 24/7 via smartphones, catering to global users regardless of location.
- Lower Fees: Many instant money apps charge minimal or zero fees for domestic transfers, undercutting traditional remittance services.
- Integration: Seamless linking with bank accounts, cryptocurrency wallets, and even loyalty programs (e.g., Starbucks rewards).
- Data-Driven Insights: Some apps provide spending analytics or credit-building tools, turning transactions into financial management resources.
Comparative Analysis
| Feature | Instant Money App (e.g., Revolut) | Traditional Bank Transfer |
|---|---|---|
| Processing Time | 1–10 seconds (same-day) | 1–3 business days |
| Fees | $0–$5 for domestic; higher for FX | $0–$30 (varies by bank) |
| Availability | 24/7, global coverage | 9 AM–5 PM, limited to bank hours |
| Security Risks | Higher fraud potential (phishing, SIM swapping) | Lower risk (regulated, insured) |

Future Trends and Innovations
The next frontier for instant money apps lies in AI-driven fraud prevention and central bank digital currencies (CBDCs). Machine learning models are already detecting anomalies in real time, reducing false positives in transaction flags. Meanwhile, CBDCs—like China’s digital yuan—could integrate with instant money apps, enabling government-backed, instant settlements without intermediaries.Another trend is embedded finance, where instant money features are baked into non-financial platforms (e.g., Uber’s tipping system or Shopify’s checkout). This blurs the line between commerce and banking, creating stickier ecosystems. However, regulatory hurdles—such as anti-money laundering (AML) compliance—will dictate how quickly these innovations scale.
Conclusion
Instant money apps are more than a convenience; they’re a redefinition of financial infrastructure. Their ability to democratize access, reduce friction, and adapt to user needs positions them as a cornerstone of the cashless economy. Yet, their success hinges on balancing innovation with responsibility—ensuring security, transparency, and inclusivity remain priorities.As technology evolves, the line between "instant" and "real-time" will continue to blur, with apps potentially offering sub-second settlements. For consumers and businesses, the key takeaway is clear: the future of money is now, and those who leverage instant money apps effectively will gain a competitive edge.
Comprehensive FAQs
Q: Are instant money apps safe to use?
A: Most reputable instant money apps employ encryption, two-factor authentication, and fraud monitoring. However, risks like phishing or SIM swapping persist. Always use apps with regulatory licenses (e.g., FCA, FinCEN) and avoid sharing OTPs or login credentials.
Q: Can I use an instant money app for international transfers?
A: Yes, but fees and exchange rates vary. Apps like Wise or Remitly specialize in cross-border instant transfers, often offering better rates than banks. Always compare costs—some apps charge hidden conversion fees.
Q: Do instant money apps affect my credit score?
A: Generally, no. Instant transfers don’t appear on credit reports unless linked to a credit-building feature (e.g., Chime’s early direct deposit). However, excessive cash advances or overdrafts via these apps can impact your score if reported to credit bureaus.
Q: What happens if I send money to the wrong recipient?
A: Most apps allow reversals within 24–48 hours if you act quickly. Some (like Zelle) require immediate action, while others (e.g., PayPal) may offer chargeback options. Always double-check recipient details before confirming.
Q: Are there limits on how much I can send instantly?
A: Yes. Daily/weekly limits vary by app and account verification level. For example, Venmo caps unverified users at $299.99/day, while banks may impose higher limits for verified instant money services. Business accounts often have separate thresholds.
Q: Can I get my money back if the app shuts down?
A: Funds held in instant money apps are typically insured up to $250,000 (U.S.) if linked to a FDIC-covered bank account. However, unclaimed balances in defunct apps may be unrecoverable. Always withdraw funds regularly or use apps with strong financial backing.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of versiliasolutions.oneagency.co.