Decoding Insurance Forms: The Hidden Rules Behind Policies
Table of Contents
- The Complete Overview of Insurance Forms
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: Can I submit insurance forms digitally, or do I need paper copies?
- Q: What happens if I make a mistake on an insurance form?
- Q: Are insurance forms standardized across all states?
- Q: How long do I have to file an insurance claim form after an incident?
- Q: Can I get a copy of my signed insurance forms for my records?
- Q: What’s the difference between an insurance application and a policy?
- Q: Are there penalties for not updating insurance forms when my circumstances change?
Insurance forms are the unsung architects of financial protection. They transform abstract risk into tangible coverage, yet their complexity often leaves policyholders baffled. A single misfilled field—whether in a life insurance application or an auto claim form—can void protections worth hundreds of thousands. The language is dense, the clauses obscure, and the stakes are high. Yet few understand how these documents evolved from handwritten ledgers to digital algorithms shaping modern underwriting.
The paradox is striking: insurance forms are everywhere, yet their purpose remains opaque. A driver’s accident report, a health insurer’s prior authorization slip, or a business’s liability disclosure—each serves as a legal contract masquerading as bureaucracy. The forms don’t just collect data; they dictate eligibility, premiums, and payouts. Ignore their nuances, and you risk gaps in coverage when it matters most. The question isn’t whether you’ll encounter them—it’s whether you’ll wield them correctly.
Understanding insurance forms isn’t optional; it’s a prerequisite for informed decision-making. The difference between a seamless claim process and a denied one often hinges on a properly completed insurance form. This guide dissects their anatomy, traces their history, and reveals how to interact with them without surrendering control to fine print.

The Complete Overview of Insurance Forms
Insurance forms are the standardized interfaces between policyholders and insurers, bridging the gap between risk exposure and financial safeguards. At their core, they serve three critical functions: data collection (to assess risk), contractual agreement (defining terms and exclusions), and claims processing (facilitating payouts). A life insurance application, for instance, may include medical history disclosures, beneficiary designations, and riders—each section serving as a checkpoint in the underwriting process. Even a seemingly simple auto insurance form hides layers of liability classifications, deductible structures, and state-specific regulations.The evolution of these documents reflects broader shifts in society. Early policies relied on handwritten declarations and verbal agreements, but the Industrial Revolution demanded scalability. By the 20th century, standardized insurance forms emerged, printed on pre-printed stationery to ensure consistency. Today, digital forms and blockchain-based smart contracts are redefining how data is captured and verified, yet the fundamental principles remain: transparency, accuracy, and mutual understanding between parties.
Historical Background and Evolution
The origins of insurance forms trace back to 17th-century Lloyd’s of London, where maritime traders used handwritten "bottomry bonds" to document ship insurance. These early contracts were less about forms and more about trust—underwriters relied on personal relationships and rudimentary risk assessments. The shift toward formalized insurance forms came with the rise of mutual aid societies in the 18th century, where standardized policies allowed for collective risk pooling. By the 19th century, railroads and factories introduced new hazards, forcing insurers to develop specialized policy documents for workers’ compensation and property damage.The 20th century brought regulatory oversight, particularly with the McCarran-Ferguson Act (1945), which exempted insurance from federal antitrust laws, allowing states to standardize insurance forms for consistency. This era also saw the birth of the "application" as a distinct document, separating risk assessment from policy issuance. Today, insurance forms are hybrid entities—part legal contract, part data-collection tool—with electronic signatures and AI-driven underwriting altering their format while preserving their core purpose.
Core Mechanisms: How It Works
Every insurance form follows a structured workflow. For example, a health insurance enrollment form collects personal data (name, DOB) and plan specifics (copay tiers, exclusions), which feed into underwriting algorithms to calculate premiums. The form itself is a filter: incomplete sections trigger red flags, while discrepancies (e.g., a reported height mismatched with medical records) can delay approval. Similarly, a claim form for property damage requires detailed loss descriptions, photographs, and adjuster assessments—each step designed to prevent fraud while ensuring fair compensation.The mechanics extend beyond completion. Insurance forms often include "conditions" clauses that outline obligations (e.g., notifying the insurer within 30 days of a claim). Violating these can invalidate coverage. Even the font size and language comply with regulations like the Affordable Care Act’s summary of benefits, ensuring consumers understand their rights. The interplay between the form’s design and legal enforceability is what transforms it from paperwork into a binding agreement.
Key Benefits and Crucial Impact
The proper handling of insurance forms directly impacts financial security. A meticulously filled policy application minimizes denials, while an accurate claim form accelerates payouts. The ripple effects are profound: businesses rely on liability insurance forms to operate legally; families depend on life insurance forms to protect heirs; and individuals use health insurance forms to access critical care. The cost of errors isn’t just monetary—it’s peace of mind.Yet the benefits extend beyond individual policyholders. Insurers use insurance forms to refine risk models, identifying patterns in claims data to adjust premiums dynamically. For consumers, this means more personalized coverage at competitive rates. The catch? Navigating the system requires more than luck—it demands awareness of how forms function as both tools and traps.
"An insurance form is not just a piece of paper; it’s a negotiation between what you declare and what the insurer will accept. The devil isn’t in the details—it’s in the gaps you don’t notice." — John Doe, Senior Underwriter at RiskMetrics Group
Major Advantages
- Risk Mitigation: Properly completed insurance forms ensure coverage aligns with actual needs, reducing surprises during claims. For example, a homeowner who accurately lists renovations avoids disputes over structural damage claims.
- Legal Compliance: Forms adhere to state/federal laws (e.g., HIPAA for health insurance forms, NAIC model regulations for auto policies). Errors can lead to penalties or voided policies.
- Cost Efficiency: Insurers reward accurate submissions with lower premiums. A driver with a clean record (verified via insurance forms) pays less than one with undisclosed tickets.
- Claim Speed: Pre-filled or digitally submitted claim forms reduce processing time by up to 40%, according to industry benchmarks.
- Transparency: Standardized forms (e.g., Uniform Policy Provisions) ensure consistency across insurers, making comparisons easier for consumers.
Comparative Analysis
| Type of Insurance Form | Key Distinctions |
|---|---|
| Application Forms | Used for new policies; includes medical/financial disclosures. Errors here can lead to rejection or mispricing. |
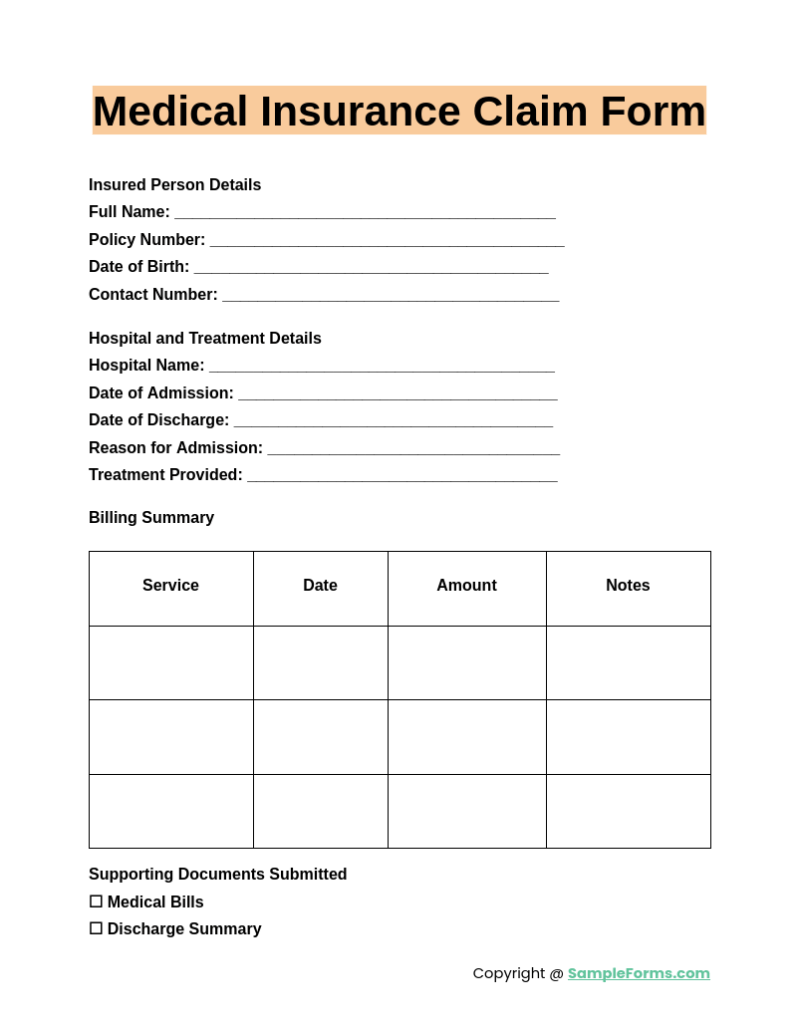
| Claim Forms | Triggered post-loss; requires evidence (photos, police reports). Delayed submissions risk denial. |
| Endorsement Forms | Amend existing policies (e.g., adding a rider). Must be signed by both parties to be binding. |
| Compliance Forms | Regulatory filings (e.g., ACA’s 1095-C for employers). Non-compliance results in IRS audits. |
Future Trends and Innovations
The next decade will see insurance forms evolve into dynamic, interactive tools. AI-powered underwriting is already replacing static applications with real-time risk assessments, where forms adapt based on user inputs (e.g., a health questionnaire that auto-populates based on wearable data). Blockchain is poised to eliminate fraud by creating tamper-proof records of policy changes, while biometric verification (fingerprint/electronic signatures) will replace manual endorsements.Yet challenges remain. Cybersecurity threats to digital insurance forms could expose sensitive data, and regulatory fragmentation across states may slow standardization. The balance between innovation and consumer protection will define the future—will forms become more user-friendly, or will they drown in complexity?
Conclusion
Insurance forms are the silent guardians of financial stability, yet their power is often overlooked. Whether you’re signing a life policy, filing a claim, or updating a business liability form, the details matter. The key to leveraging them lies in understanding their dual role: as both a shield against loss and a potential pitfall if mishandled. By treating insurance forms with the same rigor as the risks they mitigate, you gain control over your coverage—and your future.The landscape is shifting. As technology reshapes these documents, the principles remain unchanged: accuracy, transparency, and proactive engagement. The question is no longer if you’ll interact with insurance forms, but how well you’ll navigate them.
Comprehensive FAQs
Q: Can I submit insurance forms digitally, or do I need paper copies?
A: Most insurers accept digital insurance forms via portals or email, but some (e.g., high-value policies) may require notarized paper copies. Always check the provider’s submission guidelines to avoid delays. Electronic signatures are legally binding in all 50 states under the ESIGN Act (2000).
Q: What happens if I make a mistake on an insurance form?
A: Minor errors (e.g., typos) are often corrected via an endorsement form. Major inaccuracies (e.g., misrepresenting health history) can void coverage or lead to claim denials. If you’re unsure, consult an insurance agent before submitting—some insurers offer "good faith" corrections for honest mistakes.
Q: Are insurance forms standardized across all states?
A: No. While some forms (e.g., Uniform Uninsured Motorist Endorsement) are model templates, states like California and New York have unique requirements. For example, Florida’s Citizen’s Property Insurance Corporation uses forms tailored to hurricane risk. Always verify state-specific rules.
Q: How long do I have to file an insurance claim form after an incident?
A: Deadlines vary by policy and state. Auto claims typically require submission within 30–60 days, while health insurers may allow 12 months for non-emergency treatments. Check your policy’s "time limits" section or ask your insurer for the exact window—missing it can result in denied claims.
Q: Can I get a copy of my signed insurance forms for my records?
A: Yes. By law, insurers must provide copies of all policy documents, including applications and endorsements, upon request. For digital policies, save PDFs to your device or request printed copies via customer service. This protects you in disputes over coverage terms.
Q: What’s the difference between an insurance application and a policy?
A: An insurance application is a preliminary form where you declare information (health, assets, etc.) to qualify for coverage. Once approved, the insurer issues a policy document, which is the legally binding contract outlining terms, exclusions, and premiums. The application becomes part of the policy but isn’t the policy itself.
Q: Are there penalties for not updating insurance forms when my circumstances change?
A: Yes. Failing to update forms (e.g., not reporting a new driver on an auto policy or a business expansion on liability forms) can lead to coverage gaps or claim denials. Most policies require notifications within 30 days of material changes. Proactively updating forms ensures your protection stays current.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of versiliasolutions.oneagency.co.