How Insurance Payments Processing Works: The Hidden Engine of Claims Efficiency
Table of Contents
- The Complete Overview of Insurance Payments Processing
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: How long does the average insurance claim take to process?
- Q: Can insurance payments be delayed due to fraud investigations?
- Q: What role does blockchain play in insurance payments processing?
- Q: How do insurers ensure compliance during payments?
- Q: What’s the biggest challenge in scaling insurance payments processing?
Insurance payments processing isn’t just about transferring funds—it’s the backbone of trust between insurers and policyholders. Behind every approved claim lies a meticulously orchestrated system of verification, fraud detection, and regulatory compliance, all designed to balance speed with accuracy. The stakes are high: delays cost businesses millions in operational inefficiencies, while errors erode customer confidence. Yet, the mechanics of this process remain opaque to most, buried in layers of legacy systems and emerging fintech innovations.
At its core, insurance payments processing represents the intersection of financial risk assessment and operational efficiency. It’s where underwriting meets payouts, where data analytics collide with human oversight, and where automation clashes with the need for transparency. The system’s effectiveness directly influences an insurer’s profitability, reputation, and ability to scale—yet few stakeholders fully grasp its complexity. From the moment a claim is filed to the final disbursement, every step is governed by protocols that blend technology with human judgment, often under pressure from tightening regulatory scrutiny.
The evolution of insurance payments processing mirrors broader shifts in the financial services industry. What began as manual ledger entries and paper-based approvals has transformed into a high-speed, data-driven ecosystem. Today, insurers leverage AI-driven fraud detection, blockchain for secure transactions, and real-time analytics to streamline workflows. But the transition hasn’t been seamless—legacy systems, compliance hurdles, and cybersecurity threats continue to challenge even the most advanced insurers. Understanding this landscape isn’t just academic; it’s critical for businesses navigating an industry where efficiency and accuracy are non-negotiable.
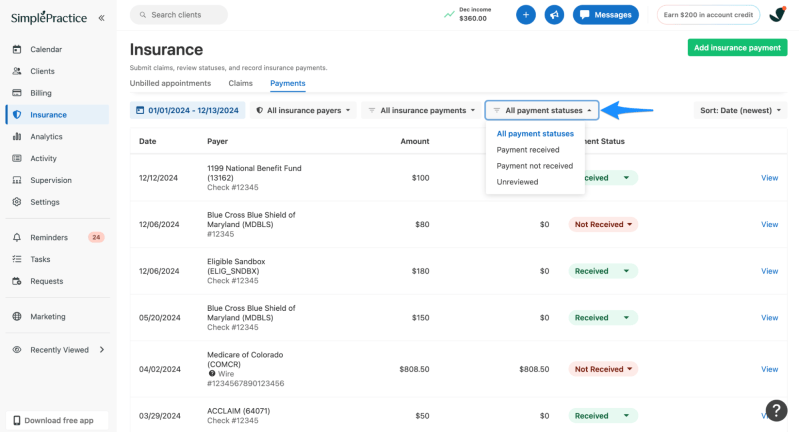
The Complete Overview of Insurance Payments Processing
The term insurance payments processing encompasses the entire lifecycle of a claim—from submission to settlement—including validation, adjudication, and fund disbursement. It’s a multi-stage pipeline where each phase demands precision: claims are triaged against policy terms, evidence is scrutinized for authenticity, and payments are routed through compliance checks before reaching beneficiaries. The process isn’t linear; it’s a dynamic interplay of technology, human expertise, and external factors like economic conditions or regulatory changes. For instance, a property insurance claim triggered by a natural disaster may involve coordination with third-party adjusters, municipal damage assessments, and even government relief programs—all while adhering to strict deadlines.What distinguishes modern insurance payments processing from its predecessors is the integration of predictive analytics and automated workflows. Traditional models relied on static underwriting rules and batch processing, leading to delays that frustrated policyholders. Today, insurers use machine learning to flag anomalies in claims data, reducing fraud by up to 30% in some cases. Meanwhile, APIs and cloud-based platforms enable seamless integration with banks, payment gateways, and even IoT devices (e.g., smart home sensors that auto-trigger claims for water leaks). The result? Faster turnaround times, lower operational costs, and a more responsive customer experience. However, this shift has also introduced new vulnerabilities, such as data privacy risks and the potential for algorithmic bias in automated decisions.
Historical Background and Evolution
The origins of insurance payments processing trace back to the 17th century, when Lloyd’s of London pioneered marine insurance with handwritten policies and manual claim settlements. Early systems were rudimentary: underwriters would physically inspect damaged ships, verify cargo manifests, and negotiate payouts over weeks—or even months. The Industrial Revolution accelerated the need for standardization, leading to the creation of actuarial science in the 19th century. By the early 20th century, typewriters and carbon paper replaced quill pens, but the core process remained labor-intensive, with claims processed in batches and payments issued via check.The digital revolution of the 1980s and 1990s marked a turning point. Insurers adopted mainframe computers to automate policy administration, and by the 2000s, the internet enabled online claim submissions. However, the real inflection point came with the rise of insurance payments processing as a specialized function. Legacy systems, built for batch processing, struggled to handle the volume of real-time transactions. Enter cloud computing and Software-as-a-Service (SaaS) platforms, which allowed insurers to outsource non-core functions like claims processing to third-party vendors. Today, the industry is in a hybrid phase: while some insurers still rely on monolithic ERP systems, others have adopted microservices architectures that decouple claims validation from payment execution, improving agility.
Core Mechanisms: How It Works
The anatomy of insurance payments processing begins with the claim submission, where policyholders provide details via digital portals, mobile apps, or phone calls. The system first routes the claim to a triage module, which checks for completeness and flags obvious red flags (e.g., duplicate submissions or claims exceeding policy limits). Valid claims proceed to the adjudication phase, where underwriting rules—encoded in decision trees or AI models—determine eligibility. For example, a health insurer might cross-reference a medical claim against a patient’s treatment history to detect upcoding.Once approved, the claim enters the insurance payments processing pipeline, where funds are prepared for disbursement. This stage involves several critical sub-processes:
1. Fraud Detection: Algorithms compare claim patterns against known fraud indicators (e.g., sudden spikes in claims from a single provider).
2. Compliance Checks: Payments are screened against sanctions lists, tax laws, and anti-money laundering (AML) regulations.
3. Payment Routing: Funds are transferred via ACH, wire, or digital wallets, with some insurers offering instant payouts for low-risk claims.
4. Audit Trails: Every transaction is logged for regulatory reporting, with immutable records maintained for disputes.
The final step—payout—is where the process intersects with the policyholder’s financial ecosystem. Insurers must navigate bank cutoffs, currency conversions (for international claims), and even cryptocurrency payouts in niche markets. Post-payment, the system may trigger follow-ups, such as requesting additional documentation or scheduling repairs for property claims.
Key Benefits and Crucial Impact
The efficiency of insurance payments processing directly correlates with an insurer’s bottom line. Faster claim settlements reduce administrative overhead, while lower error rates minimize financial losses from fraud or miscalculations. For policyholders, a streamlined process translates to quicker access to funds during crises—whether it’s medical emergencies or disaster recovery. The ripple effects extend to the broader economy: insurers with optimized insurance payments processing can offer competitive premiums, attracting more customers and expanding market share.Beyond financial metrics, the impact of this system is cultural. Insurers that prioritize transparency and speed build stronger trust with clients, fostering long-term loyalty. Conversely, delays or opaque processes erode confidence, driving policyholders to competitors. The stakes are particularly high in high-frequency sectors like auto insurance, where claims volumes can spike after natural disasters. Here, the ability to process thousands of claims in parallel—without sacrificing accuracy—can mean the difference between profitability and insolvency.
> "Insurance payments processing isn’t just about moving money; it’s about moving trust. The companies that master this will define the industry’s future." — Jane Carter, Former CFO of a Top 20 Global Insurer
Major Advantages
- Cost Reduction: Automation cuts processing costs by up to 50% by eliminating manual data entry and reducing reliance on third-party adjusters.
- Fraud Mitigation: AI-driven anomaly detection reduces fraudulent claims by 20–40%, preserving premium revenue.
- Regulatory Compliance: Real-time validation ensures adherence to laws like the Affordable Care Act (health insurance) or GDPR (data privacy).
- Customer Satisfaction: Faster payouts (e.g., same-day settlements for low-risk claims) improve Net Promoter Scores (NPS) by 15–25%.
- Scalability: Cloud-based systems handle seasonal spikes (e.g., hurricane seasons) without infrastructure bottlenecks.
Comparative Analysis
| Traditional Processing | Modern Automated Processing |
|---|---|
| Manual review by underwriters; batch processing (weekly/monthly). | AI-driven triage with real-time adjudication; 24/7 operation. |
| High error rates (1–3% due to human oversight). | Error rates below 0.5% with machine learning validation. |
| Dependent on paper trails; slow dispute resolution. | Blockchain-enabled audit trails; automated dispute mediation. |
| Limited integration with external systems (e.g., banks). | Seamless API connections for instant payouts and data sharing. |

Future Trends and Innovations
The next decade of insurance payments processing will be shaped by three disruptive forces: hyper-personalization, embedded finance, and regulatory tech (RegTech). Insurers are already experimenting with dynamic pricing models, where premiums and payouts adjust in real-time based on telematics data (e.g., auto insurers offering discounts for safe driving). Embedded finance—such as instant claim settlements via buy-now-pay-later (BNPL) integrations—will blur the lines between insurance and banking, creating new revenue streams. Meanwhile, RegTech solutions will automate compliance reporting, reducing the burden on insurers to manually reconcile transactions across jurisdictions.Another frontier is insurance payments processing in the metaverse. Virtual economies will demand new forms of coverage (e.g., digital asset theft, NFT damage), requiring insurers to develop specialized payout mechanisms for cryptocurrencies and decentralized finance (DeFi) platforms. Blockchain’s potential to create tamper-proof claim records could also revolutionize fraud prevention, though scalability and interoperability remain challenges. As these innovations unfold, the industry’s ability to adapt will hinge on balancing technological ambition with operational pragmatism—ensuring that speed doesn’t come at the cost of reliability.
Conclusion
Insurance payments processing is far more than a back-office function—it’s the linchpin of the insurance value chain. Its evolution reflects broader trends in finance: the shift from manual to automated, from siloed systems to interconnected ecosystems. The insurers that thrive in this landscape will be those that treat insurance payments processing as a strategic asset, not just a cost center. They’ll leverage data to predict risks before claims arise, deploy AI to reduce fraud without sacrificing empathy, and embrace innovation while maintaining the human touch that defines trust.The future belongs to those who can harmonize technology with transparency. As the industry hurtles toward real-time settlements and AI-driven underwriting, the companies that master insurance payments processing will redefine what it means to protect—and serve—their customers.
Comprehensive FAQs
Q: How long does the average insurance claim take to process?
A: Processing times vary by insurer and claim type. Auto insurance claims typically resolve in 14–30 days, while complex medical or property claims can take 60–90 days. Insurers using automated insurance payments processing systems often achieve sub-7-day turnaround for straightforward claims.
Q: Can insurance payments be delayed due to fraud investigations?
A: Yes. If a claim triggers fraud alerts (e.g., suspicious patterns or mismatched documentation), insurers may suspend payments for further review. Automated systems can expedite this process by flagging high-risk claims within hours, but manual investigations may extend timelines by weeks.
Q: What role does blockchain play in insurance payments processing?
A: Blockchain enhances insurance payments processing by providing immutable audit trails, reducing fraud, and enabling smart contracts for automated payouts. For example, a blockchain-based system could auto-release funds once predefined conditions (e.g., a flight delay confirmation) are met, eliminating intermediary delays.
Q: How do insurers ensure compliance during payments?
A: Compliance is enforced through layered checks: AML screening, tax withholding (e.g., IRS Form 1099 for large payouts), and sanctions list verification. RegTech tools automate these checks, cross-referencing payments against global databases to flag violations before disbursement.
Q: What’s the biggest challenge in scaling insurance payments processing?
A: The primary challenge is balancing speed with accuracy, especially as claim volumes surge (e.g., post-disaster). Legacy systems lack the flexibility to handle real-time spikes, while over-reliance on automation risks false rejections. Insurers mitigate this by adopting hybrid models—combining AI for triage with human oversight for edge cases.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of versiliasolutions.oneagency.co.