How Insurance Verification Certification Transforms Risk Management in 2024
Table of Contents
- The Complete Overview of Insurance Verification Certification
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: What is the difference between insurance verification certification and general compliance training?
- Q: How long does it typically take to obtain insurance verification certification?
- Q: Are there industry-recognized certifications specifically for insurance verification?
- Q: Can insurance verification certification help reduce claim processing times?
- Q: What are the emerging technologies transforming insurance verification certification?
- Q: Is insurance verification certification mandatory for certain roles?
The insurance industry operates on trust—yet trust requires proof. Behind every policy issued, every claim processed, and every underwriting decision lies a critical layer of validation: insurance verification certification. This specialized credential isn’t just a checkbox; it’s the backbone of operational integrity, ensuring that providers adhere to regulatory standards while minimizing exposure to fraudulent activities. Without it, the system risks collapsing under the weight of misrepresented risks, delayed payouts, and legal vulnerabilities.
Consider the ripple effect when a single unverified policy slips through the cracks. A 2023 report by the Coalition Against Insurance Fraud estimated that $80 billion in fraudulent claims were attempted annually in the U.S. alone—many of which could have been intercepted by rigorous insurance verification certification protocols. The stakes are higher than ever, as digital transformation accelerates the pace of transactions while expanding attack surfaces for bad actors. Yet, despite its urgency, the topic remains shrouded in ambiguity for many stakeholders: What exactly does this certification entail? How does it differ from standard compliance training? And why is it becoming non-negotiable for insurers, brokers, and third-party verifiers?
The answer lies in the intersection of technology, regulation, and human expertise. Insurance verification certification isn’t merely about ticking compliance boxes—it’s about embedding a culture of precision into every stage of the insurance lifecycle, from policy inception to claims resolution. For professionals navigating this landscape, understanding its nuances isn’t optional; it’s a strategic imperative. Below, we dissect its evolution, mechanics, and transformative impact—along with what lies ahead.
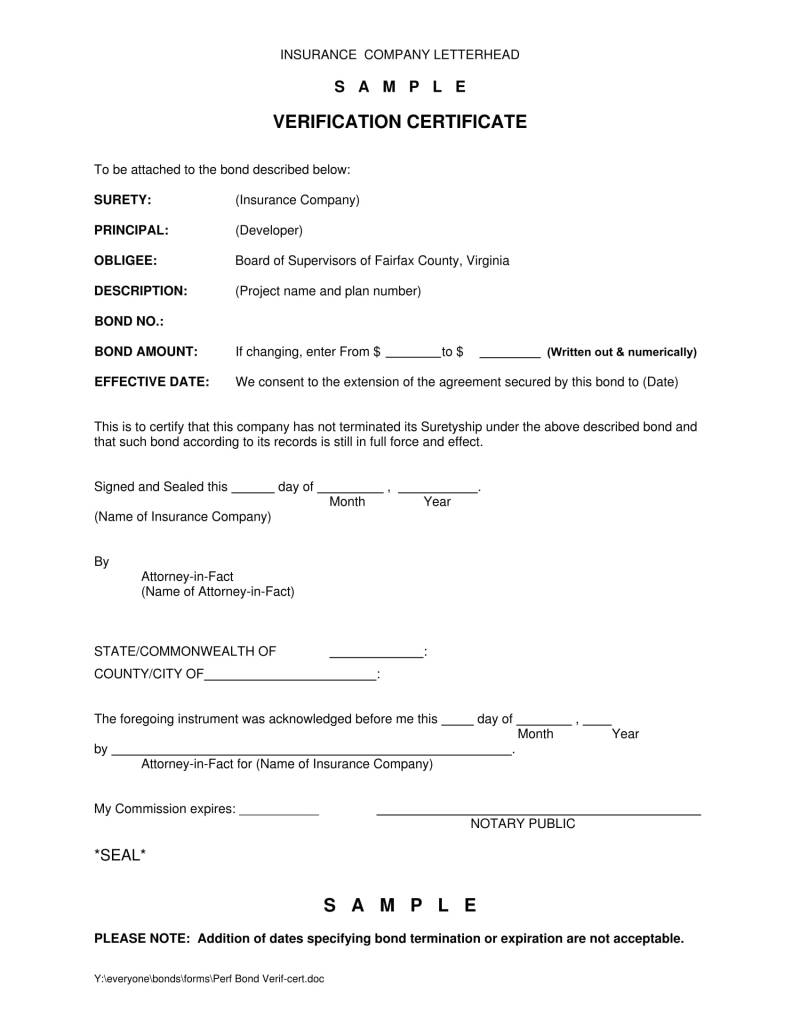
The Complete Overview of Insurance Verification Certification
Insurance verification certification refers to a structured program designed to validate the accuracy of policyholder information, coverage details, and claims submissions against regulatory benchmarks and industry standards. Unlike generic compliance training, this certification focuses on active verification—the process of cross-referencing data with authoritative sources (e.g., government databases, credit bureaus, or insurer-specific algorithms) to confirm legitimacy. The goal is twofold: to prevent fraudulent submissions and to ensure that valid claims are processed without unnecessary delays.
Certification programs vary by jurisdiction and provider, but they typically include modules on data integrity, fraud detection techniques, and the use of verification tools such as Electronic Data Interchange (EDI) systems or blockchain-ledger audits. For instance, the National Association of Insurance Commissioners (NAIC) mandates specific verification protocols for property and casualty insurers, while private certifications (e.g., Certified Insurance Service Representative (CISR)) incorporate verification components into broader professional development tracks. The rise of insurance verification certification reflects a broader industry shift toward proactive risk mitigation, where verification isn’t an afterthought but a foundational practice.
Historical Background and Evolution
The origins of insurance verification certification can be traced to the early 20th century, when insurers began formalizing underwriting standards to combat rampant fraud. The McCarran-Ferguson Act (1945) further solidified state-level oversight, requiring insurers to implement verification measures to align with solvency laws. However, the modern iteration emerged in the 1990s with the advent of digital databases, which enabled real-time cross-checking of policyholder identities and claim histories.
Today, the landscape is defined by three key milestones: the Patriot Act (2001), which tightened verification requirements for financial transactions; the Affordable Care Act (2010), which introduced stringent identity verification for healthcare insurers; and the General Data Protection Regulation (GDPR, 2018), which imposed strict data accuracy obligations on EU-based insurers. These regulations didn’t just create compliance mandates—they accelerated the development of insurance verification certification as a specialized field. Now, certifications like the Certified Fraud Examiner (CFE) or the Insurance Verification Specialist (IVS) credential are increasingly sought after by employers as a signal of expertise in this domain.
Core Mechanisms: How It Works
The verification process begins with data ingestion, where insurers or third-party verifiers collect policyholder information through secure portals or automated systems. This data is then subjected to a multi-layered validation protocol: identity verification (e.g., government-issued ID checks), coverage validation (e.g., cross-referencing with motor vehicle records or property titles), and claims authentication (e.g., comparing medical records with submitted bills). Advanced systems leverage machine learning to flag anomalies, such as discrepancies in addresses or employment histories, which may indicate fraud.
Certification programs typically require professionals to demonstrate proficiency in these mechanisms through case studies, simulations, and exams. For example, a Certified Insurance Verification Professional (CIVP) candidate might be tested on their ability to interpret NAIC Model Laws or use tools like LexisNexis Risk Solutions to verify claimant identities. The certification itself often includes ongoing education to adapt to emerging threats, such as synthetic identity fraud or deepfake-enabled claim submissions. The result is a workforce equipped to navigate the complexities of modern verification—where technology and human judgment must coexist.
Key Benefits and Crucial Impact
The adoption of insurance verification certification isn’t just a regulatory checkbox; it’s a competitive differentiator. Insurers with certified verification teams experience 30–50% reductions in fraud-related losses, according to a 2023 study by the Federal Bureau of Investigation (FBI). Beyond cost savings, certification enhances operational efficiency by streamlining claims processing and reducing disputes. For policyholders, it translates to faster payouts and greater confidence in the integrity of their coverage.
Yet the impact extends beyond financial metrics. In an era where data breaches and identity theft are rampant, insurance verification certification serves as a bulwark against cyber threats. Certified professionals are trained to recognize phishing attempts, spoofed documents, and other tactics used to exploit verification gaps. This proactive stance aligns with broader industry trends toward ethical risk management, where transparency and accuracy are prioritized over reactive damage control.
"Verification isn’t just about catching fraud—it’s about building trust in an ecosystem where every transaction hinges on accurate information."
— Dr. Elena Vasquez, Chief Compliance Officer, Allianz Global Corporate & Specialty
Major Advantages
- Fraud Prevention: Certified verifiers use advanced algorithms and manual reviews to detect patterns indicative of fraud, such as inflated claims or staged accidents.
- Regulatory Compliance: Certification ensures adherence to laws like the Fair Credit Reporting Act (FCRA) and GDPR, avoiding costly penalties.
- Operational Efficiency: Automated verification tools integrated with certified workflows reduce processing times by up to 40%, accelerating claim settlements.
- Enhanced Reputation: Insurers with certified teams are perceived as more trustworthy, attracting clients wary of fraudulent practices in the industry.
- Future-Proofing: Certification programs often include training on emerging technologies (e.g., AI-driven verification or biometric authentication), preparing professionals for industry shifts.
Comparative Analysis
| Aspect | Traditional Compliance Training | Insurance Verification Certification |
|---|---|---|
| Focus | General regulatory knowledge (e.g., state laws, ethical standards). | Specialized in data validation, fraud detection, and verification tools. |
| Certification Body | Issued by industry associations (e.g., American Institute for Chartered Property Casualty Underwriters, The Institutes). | Offered by niche providers (e.g., Certified Insurance Verification Professional (CIVP), NAIC-accredited programs). |
| Skill Development | Covers broad topics like policy interpretation or customer service. | Hones technical skills in EDI systems, blockchain audits, and forensic analysis. |
| Industry Demand | Widespread but not specialized. | High demand in underwriting, claims, and third-party verification roles. |

Future Trends and Innovations
The next frontier for insurance verification certification lies in the integration of artificial intelligence and decentralized identity solutions. AI-powered verification systems are already capable of analyzing unstructured data (e.g., handwritten claim forms or voice recordings) to detect inconsistencies, while blockchain-based identity networks promise to eliminate single points of failure in verification chains. Certification programs are evolving to include modules on these technologies, ensuring professionals can leverage them ethically and effectively.
Additionally, the rise of insurtech startups is democratizing verification tools, making advanced certification accessible to smaller insurers and brokers. However, this trend also introduces challenges: as verification becomes more automated, the role of human expertise may shift toward oversight and judgment, requiring updated certification standards. The future of insurance verification certification will likely emphasize hybrid models—where technology handles high-volume, low-risk validations, and certified experts intervene in complex or ambiguous cases.
Conclusion
Insurance verification certification is more than a credential—it’s a commitment to accuracy in an industry where precision directly impacts lives and livelihoods. As fraudsters grow more sophisticated, the tools and expertise behind verification must evolve in kind. For professionals, pursuing certification isn’t just a career move; it’s a pledge to uphold the integrity of the insurance ecosystem. For insurers, investing in certified verification teams is a strategic imperative to stay ahead of risks, meet regulatory demands, and foster trust with policyholders.
In an era where data is both an asset and a liability, the role of insurance verification certification will only grow in prominence. The question isn’t whether to adopt it—but how to integrate it into operations in a way that balances efficiency with ethical rigor. The answer lies in continuous learning, adaptive technology, and a workforce equipped to navigate the complexities of verification in the digital age.
Comprehensive FAQs
Q: What is the difference between insurance verification certification and general compliance training?
A: While general compliance training covers broad regulatory knowledge (e.g., state insurance laws, ethical standards), insurance verification certification focuses specifically on active data validation, including fraud detection techniques, verification tool proficiency, and forensic analysis of claims. Certification programs often require hands-on assessments, such as case studies or simulations, to demonstrate practical skills.
Q: How long does it typically take to obtain insurance verification certification?
A: The duration varies by program. Entry-level certifications (e.g., Certified Insurance Service Representative (CISR) with verification modules) may take 3–6 months, while advanced certifications (e.g., Certified Fraud Examiner (CFE) or Certified Insurance Verification Professional (CIVP)) can require 1–2 years, including coursework, exams, and practical experience. Some accelerated online programs offer condensed timelines (e.g., 3–4 months).
Q: Are there industry-recognized certifications specifically for insurance verification?
A: Yes. Key certifications include:
- Certified Insurance Verification Professional (CIVP) – Focuses on underwriting and claims verification.
- Certified Fraud Examiner (CFE) – Covers fraud detection, including verification techniques.
- Insurance Verification Specialist (IVS) – Offered by niche providers like Insurance Institute of America (IIA).
Q: Can insurance verification certification help reduce claim processing times?
A: Absolutely. Certified verifiers are trained to use automated verification tools (e.g., EDI systems, AI-driven fraud detection) that streamline data validation, reducing manual review times by up to 50%. For example, a certified professional might leverage blockchain audits to instantly verify the authenticity of property damage photos, accelerating claim approvals without sacrificing accuracy.
Q: What are the emerging technologies transforming insurance verification certification?
A: The field is rapidly adopting:
- AI/ML Algorithms – Analyze unstructured data (e.g., handwritten forms, voice recordings) to detect inconsistencies.
- Biometric Verification – Uses fingerprint or facial recognition to authenticate claimants in real time.
- Blockchain Identity Networks – Creates tamper-proof records of policyholder identities and claim histories.
- Predictive Analytics – Flags high-risk claims based on historical fraud patterns.
Q: Is insurance verification certification mandatory for certain roles?
A: While not universally mandatory, many insurers and brokers now require or strongly prefer certification for roles in:
- Underwriting and policy validation.
- Claims investigation and fraud prevention.
- Third-party verification services.
- Compliance and risk management.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of versiliasolutions.oneagency.co.