How Pricing Model Insurance Shapes Risk, Profit, and Consumer Trust
Table of Contents
- The Complete Overview of Pricing Model Insurance
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: How do insurers determine the base rate for a pricing model?
- Q: Can my credit score affect my insurance premiums?
- Q: What’s the difference between "class rating" and "individual rating" in pricing models?
- Q: How do insurers handle "adverse selection" in pricing models?
- Q: Are there alternatives to traditional actuarial pricing models?
- Q: What should consumers do if they suspect their insurance premium is unfairly high?
The numbers behind insurance aren’t just spreadsheets—they’re the silent architects of financial stability for millions. Every policy, from auto to cyber liability, hinges on a pricing model insurance framework designed to balance risk, profitability, and consumer affordability. Yet these models are rarely discussed beyond industry jargon, leaving gaps in transparency that affect everything from individual premiums to systemic market resilience.
At its core, pricing model insurance is a fusion of hard data and behavioral economics. Actuaries crunch historical claims data, while underwriters factor in real-time variables like credit scores, driving habits, or even social media activity. The result? A system that feels personalized yet remains statistically sound—or at least, that’s the theory. In practice, debates rage over fairness, algorithmic bias, and whether these models overcharge vulnerable demographics.
The stakes are higher than ever. As insurers adopt AI-driven dynamic pricing, traditional actuarial methods face scrutiny. Regulators are tightening oversight, consumers demand explainability, and cyber risks introduce entirely new variables. Navigating this landscape requires understanding not just the mechanics, but the ethical and economic trade-offs embedded in every premium calculation.

The Complete Overview of Pricing Model Insurance
Pricing model insurance is the backbone of the industry’s financial viability, determining how much policyholders pay while ensuring insurers can cover losses—and turn a profit. These models are built on three pillars: risk assessment, cost allocation, and market positioning. Risk assessment relies on historical claims data, external risk factors (e.g., natural disasters, economic downturns), and predictive analytics to estimate future liabilities. Cost allocation then distributes these risks across policyholders, often using complex formulas that adjust for individual risk profiles. Finally, market positioning ensures premiums remain competitive while maintaining underwriting profitability—a delicate equilibrium that varies by region, product type, and regulatory environment.The evolution of pricing model insurance reflects broader shifts in technology and consumer expectations. What began as rudimentary manual calculations in the 19th century has transformed into sophisticated, data-driven systems. Today, insurers leverage machine learning to refine risk segmentation, while telematics in auto insurance or IoT sensors in home insurance provide real-time data feeds. Yet, despite these advancements, the fundamental question remains: How do we price risk fairly without excluding high-risk individuals or overburdening low-income policyholders? The answer lies in the interplay between actuarial science, regulatory guardrails, and ethical considerations.
Historical Background and Evolution
The origins of pricing model insurance trace back to the 18th century, when early underwriters like Lloyd’s of London relied on rudimentary risk pools and underwriting judgment. Premiums were set based on broad categories (e.g., "merchant seaman" vs. "land-based trader") with minimal data. The Industrial Revolution introduced the need for more precise models, leading to the birth of actuarial science in the 19th century. Pioneers like Edmund Halley (yes, the comet namesake) applied probability theory to life insurance, creating the first mortality tables. By the early 20th century, companies like Prudential and MetLife formalized pricing model insurance as a blend of statistical analysis and business strategy, laying the groundwork for modern underwriting.The digital revolution of the late 20th century disrupted this equilibrium. The rise of computers enabled insurers to process vast datasets, shifting from static tables to dynamic pricing models. The 1990s saw the introduction of usage-based insurance (UBI), where telematics devices in cars adjusted premiums based on driving behavior. Meanwhile, the 2000s brought predictive analytics, allowing insurers to factor in credit scores, employment history, and even ZIP codes into premium calculations. Critics argued these models disproportionately penalized low-income individuals, sparking regulatory pushback. Today, the debate centers on algorithmic fairness—whether AI-driven pricing model insurance systems inherently discriminate or can be audited for bias.
Core Mechanisms: How It Works
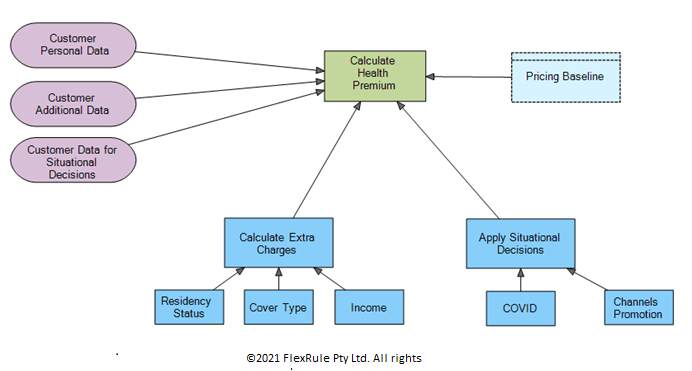
Understanding pricing model insurance requires dissecting its three primary components: risk classification, premium calculation, and profit loading. Risk classification segments policyholders into groups based on shared risk characteristics. For example, auto insurance might categorize drivers by age, location, and claims history, while health insurers use age, pre-existing conditions, and lifestyle factors. Premium calculation then applies a rate to each segment, derived from claims data and loss ratios. Finally, profit loading—a percentage added to cover operational costs, taxes, and insurer margins—ensures financial sustainability.The mechanics vary by product type. Property insurance, for instance, relies heavily on replacement cost estimates and regional risk factors (e.g., hurricane-prone areas). Health insurance models incorporate actuarial value (the percentage of costs covered) and risk corridors to stabilize premiums. Meanwhile, commercial insurance often uses experience rating, where premiums fluctuate based on a business’s claims history. The sophistication of these models has grown exponentially with technology, but their core function remains unchanged: to equitably distribute the cost of risk while maintaining solvency.
Key Benefits and Crucial Impact
The pricing model insurance framework serves as a critical stabilizer for both insurers and policyholders. For insurers, it ensures profitability by aligning premiums with expected losses, while for consumers, it provides access to coverage at a predictable cost. Without these models, the industry would collapse under the weight of unpredictable claims—imagine a world where insurers could only guess at future payouts. The system’s ability to adapt to new risks, from pandemics to climate change, also underscores its resilience. Yet, its impact extends beyond financials; pricing model insurance shapes societal trust in the industry, influencing everything from consumer adoption to regulatory trust.Critics argue that these models can perpetuate inequality, particularly when they rely on proxies like credit scores or neighborhood demographics. A 2023 study by the Consumer Federation of America found that low-income drivers often pay 30–50% more for auto insurance than wealthier counterparts with similar risk profiles. This disparity highlights the tension between actuarial precision and social equity—a tension that regulators are increasingly addressing through transparency laws and bias audits.
"Insurance pricing isn’t just about numbers; it’s about reflecting the human cost of risk—and ensuring that cost isn’t unfairly borne by the most vulnerable." — Robert Hunter, Director of Insurance for the Consumer Federation of America
Major Advantages
- Risk Mitigation: Pricing model insurance spreads risk across large pools, reducing individual financial exposure. For example, a single car accident’s cost is diluted among thousands of policyholders, making coverage affordable.
- Customization: Advanced models allow for personalized pricing, rewarding low-risk behavior (e.g., safe drivers get discounts) while accurately charging higher-risk individuals. This incentivizes safer choices.
- Market Stability: By ensuring premiums cover losses, these models prevent insurer insolvency, protecting policyholders from denied claims due to financial collapse.
- Innovation Driver: The need to refine pricing model insurance fuels technological advancements, from AI underwriting to blockchain-based fraud detection.
- Regulatory Compliance: Well-designed models help insurers meet solvency requirements, avoiding fines or license revocations that could destabilize the market.
Comparative Analysis
| Traditional Actuarial Models | AI/Dynamic Pricing Models |
|---|---|
|
|
|
Pros: Transparent, explainable, and stable for long-term policies. Cons: Slow to adapt to new risks (e.g., pandemics, climate change). |
Pros: Highly adaptive, can personalize premiums at granular levels. Cons: "Black box" nature raises ethical concerns; requires robust governance. |
| Best For: Large, homogeneous risk pools (e.g., group health insurance). | Best For: Niche markets (e.g., cyber insurance, usage-based auto policies). |
| Regulatory Scrutiny: Lower (but still subject to fairness reviews). | Regulatory Scrutiny: High; regulators demand algorithmic transparency and bias testing. |
Future Trends and Innovations
The next decade of pricing model insurance will be defined by three disruptive forces: hyper-personalization, regulatory tech (RegTech), and climate risk integration. Hyper-personalization will push insurers to offer "pay-as-you-live" policies, where premiums adjust in real time based on biometric data, location tracking, or even mental health trends (as seen in emerging mental health insurance models). RegTech will impose stricter audit trails for AI models, requiring insurers to prove their algorithms are free from discriminatory biases—a shift that could lead to standardized "fairness certificates" for pricing models.Climate risk will also reshape pricing model insurance, with insurers incorporating granular weather data, sea-level rise projections, and wildfire risk indices into premiums. The European Union’s push for "climate-aligned underwriting" may set a global precedent, forcing insurers to either adapt or face exclusion from high-risk markets. Meanwhile, the rise of parametric insurance—where payouts are triggered by predefined events (e.g., earthquake magnitude)—could reduce disputes over claim validity, streamlining the pricing process.
Conclusion
The pricing model insurance ecosystem is at a crossroads. On one hand, technological advancements promise unprecedented precision, allowing insurers to tailor coverage to individual risk profiles with surgical accuracy. On the other, ethical and regulatory challenges demand that these models be transparent, fair, and resilient to systemic shocks. The balance between innovation and equity will define the industry’s future—will insurers prioritize profit over fairness, or will they embrace a hybrid approach that leverages data without sacrificing social responsibility?One thing is certain: the conversation around pricing model insurance is no longer confined to actuarial textbooks. It’s now a public discourse, shaped by consumer advocacy, regulatory action, and the relentless march of technology. As policyholders grow more informed and demand greater transparency, insurers will need to rethink not just their algorithms, but their entire approach to risk—and how it’s priced.
Comprehensive FAQs
Q: How do insurers determine the base rate for a pricing model?
A: The base rate is calculated using loss ratios (claims paid divided by premiums collected) over a historical period, adjusted for inflation and underwriting expenses. Actuaries then apply a profit loading factor (typically 5–20%) to ensure solvency. For example, if an insurer pays out $60 in claims for every $100 in premiums, the base rate might start at $60, with an additional $10–$20 added for overhead and profit.
Q: Can my credit score affect my insurance premiums?
A: Yes, in many U.S. states, insurers use credit-based insurance scores (a proprietary model) to assess risk, as studies show a correlation between credit history and claim frequency. However, this practice is banned in states like California and Hawaii due to concerns about disproportionate impacts on low-income individuals. Always check your state’s regulations—some allow it only for auto or home insurance, not health.
Q: What’s the difference between "class rating" and "individual rating" in pricing models?
A: Class rating groups policyholders into broad categories (e.g., all 25-year-old drivers in urban areas) and applies a uniform premium. Individual rating tailors premiums to specific factors (e.g., your exact driving mileage, safety features in your car). Individual rating is more precise but requires robust data collection and can lead to higher premiums for high-risk individuals. Most modern pricing model insurance systems use a hybrid approach, combining class-based anchors with individual adjustments.
Q: How do insurers handle "adverse selection" in pricing models?
A: Adverse selection occurs when high-risk individuals seek more coverage while low-risk ones drop out, skewing the risk pool. Insurers mitigate this through underwriting guidelines (e.g., medical exams for life insurance), experience rating (adjusting premiums based on past claims), and mandatory coverage laws (e.g., health insurance mandates). Dynamic pricing models also help by continuously recalibrating risk profiles, though they can’t eliminate adverse selection entirely without regulatory interventions like risk pools or reinsurance.
Q: Are there alternatives to traditional actuarial pricing models?
A: Yes, emerging alternatives include:
- Peer-to-peer (P2P) insurance: Uses community-based risk sharing (e.g., Lemonade’s flat-fee model).
- Parametric insurance: Triggers payouts based on predefined events (e.g., hurricane wind speed), bypassing claims assessment.
- Blockchain-based models: Enable transparent, decentralized risk pooling (e.g., Etherisc for crop insurance).
- Social insurance hybrids: Combine market pricing with government subsidies (e.g., Obamacare’s risk adjustment transfers).
Q: What should consumers do if they suspect their insurance premium is unfairly high?
A: Start by:
- Request a risk profile review from your insurer to understand the factors influencing your premium.
- Compare quotes from competitors—some may use different pricing model insurance algorithms.
- Check for discounts (e.g., bundling, safety devices) that could lower your rate.
- File a complaint with your state’s insurance department if you believe the pricing is discriminatory or non-compliant with regulations.
- Consider usage-based programs (e.g., telematics) if your current model overcharges you due to static risk factors.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of versiliasolutions.oneagency.co.