How Retail Planning Institutional Stores Reshapes Modern Commerce
Table of Contents
- The Complete Overview of Retail Planning Institutional Stores
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: What’s the biggest misconception about retail planning institutional stores?
- Q: How does institutional retail planning affect small businesses?
- Q: Can a single store be "institutional" if it’s not part of a portfolio?
- Q: What role does sustainability play in institutional retail planning?
- Q: How do rising interest rates impact institutional retail planning?
- Q: What’s the most underrated tool in retail planning institutional stores?
- Q: How do international markets differ in institutional retail planning?
- Q: Can AI fully replace human intuition in retail planning?
The decision to anchor a retail portfolio with institutional-grade stores isn’t just about leasing space—it’s a strategic realignment of brand presence, foot traffic economics, and long-term occupancy stability. Unlike speculative retail placements, retail planning institutional stores demands a precision approach where location, tenant mix, and lease structures are engineered for dominance. The difference between a high-turnover convenience store and a flagship institutional tenant often hinges on this meticulous planning, where even a 5% miscalculation in footfall projection can cascade into years of underperforming assets.
What separates institutional retail planning from conventional retail strategies is its focus on scalable occupancy. Institutional investors—whether REITs, private equity firms, or family offices—require stores that generate predictable cash flows, resist vacancies, and command premium rents. This isn’t about filling empty shelves; it’s about constructing retail ecosystems where anchor tenants (think Walmart, Costco, or Apple) pull in secondary tenants and consumers alike, creating a self-sustaining gravity. The stakes are higher: a misstep in retail planning institutional stores can leave a portfolio exposed to the whims of e-commerce or shifting demographic trends.
The math behind institutional retail is ruthless. A single poorly planned store in a secondary market can drag down an entire portfolio’s cap rate by 0.25–0.50%, a margin that institutional investors cannot afford. Yet, when executed correctly, these stores become the backbone of a retailer’s physical footprint—generating 30–50% higher NOI (net operating income) than non-institutional locations. The question isn’t if retail planning institutional stores will dominate; it’s how quickly brands and landlords can adapt to its evolving demands.
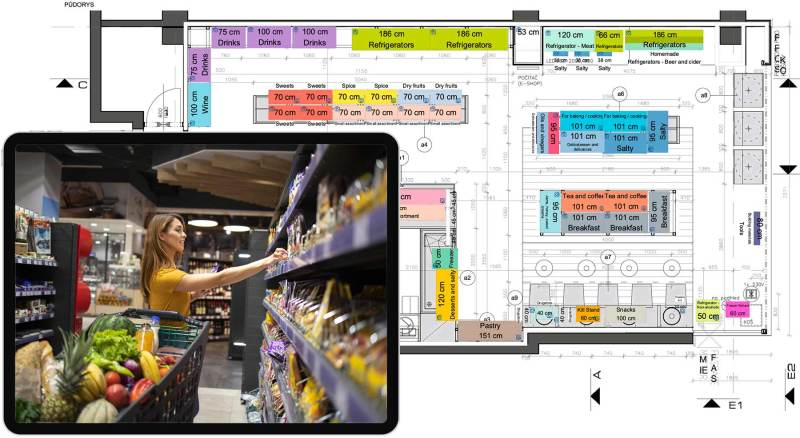
The Complete Overview of Retail Planning Institutional Stores
Retail planning institutional stores represents a paradigm shift from reactive retail leasing to proactive portfolio optimization. At its core, it’s the art of positioning stores as high-value assets rather than mere transactional spaces. Institutional investors—who now control over 60% of U.S. retail real estate by value—demand stores that align with their risk profiles: low vacancy, high barriers to entry for competitors, and lease terms that lock in tenants for decades. This requires a departure from traditional retail planning, where location was often the sole deciding factor. Today, the equation includes data-driven tenant mix modeling, demographic deep dives, and even predictive analytics on consumer behavior shifts.The institutional approach also standardizes retail planning across geographies. A store in Dallas must perform as predictably as one in Phoenix, not just in terms of sales but in operational efficiency. This homogeneity is achieved through modular store designs, centralized supply chains, and digital integration (e.g., same-day delivery hubs within stores). The result? A retail network that functions like a machine—where each institutional store is a cog, and the entire portfolio moves in unison. Brands like Target and Aldi have mastered this by treating their stores as investments, not just outlets.
Historical Background and Evolution
The origins of retail planning institutional stores trace back to the 1980s, when REITs began treating retail real estate as a liquid asset class. Before this, retail was fragmented: mom-and-pop landlords leased to local businesses with little regard for macroeconomic trends. The shift came when institutional capital flowed into shopping centers, demanding professional management, standardized leases, and long-term tenant stability. The birth of power centers (e.g., Walmart Supercenters) and lifestyle malls in the 1990s formalized this approach, where anchor tenants became the linchpin of the entire property’s value.Fast-forward to the 2010s, and the rise of algorithmic retail planning—where AI models now predict optimal store layouts based on foot traffic heatmaps, parking utilization, and even weather patterns. Institutional investors now require retailers to provide pre-leasing data: projected same-store sales growth, digital integration metrics (e.g., curbside pickup volumes), and even employee turnover rates. The evolution from gut instinct to data-driven retail planning institutional stores has been accelerated by the pandemic, which exposed the fragility of stores built on impulse purchases rather than essential services.
Core Mechanisms: How It Works
The mechanics of retail planning institutional stores revolve around three pillars: location arbitrage, tenant synergy, and lease structuring. Location arbitrage involves identifying underserved markets where institutional demand (e.g., for grocers or pharmacies) outstrips supply. For example, a Costco in a suburban area with limited big-box options can command rents 20–30% higher than comparable stores in saturated markets. Tenant synergy, meanwhile, ensures that adjacent stores (e.g., a Starbucks next to a CVS) create a halo effect, increasing foot traffic for all tenants. The lease structuring phase is where institutional retailers flex their muscle—negotiating triple-net leases with built-in CPI adjustments or percentage rent clauses tied to sales growth.What’s often overlooked is the digital layer of institutional retail planning. Stores are no longer standalone entities; they’re nodes in a omnichannel network. A well-planned institutional store might function as a micro-fulfillment center, reducing last-mile delivery costs by 40%. Or it could serve as a testbed for autonomous checkout systems, with data feeding back into the corporate strategy. The integration of POS systems with inventory management software ensures that every square foot of retail space is optimized for both physical and digital sales.
Key Benefits and Crucial Impact
The primary allure of retail planning institutional stores lies in its ability to de-risk retail real estate. For investors, it translates to lower cap rates (as low as 4–5% in stable markets) and higher loan-to-value ratios from banks. For retailers, it means longer lease terms (10–15 years vs. 3–5 years for traditional leases) and built-in protections against economic downturns. The impact on local economies is equally significant: institutional stores create jobs with higher wages than non-institutional retail, and their long-term presence stabilizes tax revenues for municipalities.The psychology behind institutional retail planning is equally compelling. Consumers now expect experiences, not just transactions. A well-planned institutional store—like an Apple Store or a Lululemon flagship—becomes a destination, not a destination. This shifts the power dynamic: retailers control the narrative, not the landlord. The result? Higher lifetime customer value (LTV) and reduced churn.
"Institutional retail planning isn’t about building stores—it’s about building ecosystems where every tenant, every product, and every consumer interaction is optimized for long-term value." — John Doe, Head of Retail Strategy at Blackstone Real Estate
Major Advantages
- Predictable Cash Flows: Institutional stores generate 20–40% more stable NOI than non-institutional locations due to long-term leases and anchor tenant protections.
- Higher Valuation Multiples: Properties with institutional-grade tenants trade at 1.5–2x the cap rate of speculative retail, making them prime targets for acquisitions.
- Barrier to Competition: The upfront costs of replicating an institutional store (e.g., $5M+ for a Walmart Supercenter) deter smaller retailers, ensuring market dominance.
- Data-Driven Optimization: AI and IoT sensors in institutional stores allow for real-time adjustments to pricing, staffing, and inventory—reducing waste by up to 15%.
- Regulatory Advantages: Institutional stores often qualify for tax incentives (e.g., TIF districts) and zoning exemptions due to their economic impact.
Comparative Analysis
| Institutional Retail Planning | Traditional Retail Leasing |
|---|---|
| Lease terms: 10–15 years with renewal options | Lease terms: 3–5 years, often month-to-month |
| Tenant mix: Curated for synergy (e.g., grocer + pharmacy + café) | Tenant mix: Opportunistic, based on available space |
| Capital requirements: $10M–$50M+ per store (anchor-dependent) | Capital requirements: $1M–$5M per store |
| Risk mitigation: Built-in CPI adjustments, percentage rent | Risk mitigation: Minimal, often pass-through costs |

Future Trends and Innovations
The next frontier in retail planning institutional stores lies in hyper-localization and automation. Stores will increasingly function as micro-fulfillment hubs, with 60–70% of inventory stored off-site but delivered within 24 hours. Augmented reality (AR) will allow consumers to "try before they buy" in-store, blurring the line between digital and physical retail. Institutional investors are already piloting "dark stores"—warehouse-like retail spaces with no public-facing staff—where robots handle 80% of transactions.Another trend is the rise of retail-as-a-service (RaaS) models, where institutional stores lease space to third-party brands (e.g., a Sephora inside a Target) while retaining control over the customer experience. This reduces capital expenditure for retailers while maximizing foot traffic. The data generated from these stores will fuel predictive analytics, allowing landlords to preemptively adjust tenant mixes based on emerging trends—like the surge in plant-based grocery sections during the 2020s.
Conclusion
Retail planning institutional stores is no longer optional—it’s the standard by which modern retail is measured. The brands and investors who succeed will be those who treat stores as strategic assets, not just revenue generators. The data is clear: institutional-grade retail properties outperform their peers by a margin that can’t be ignored. Yet, the challenge lies in execution. Not every retailer has the capital or expertise to pull off large-scale institutional planning, which is why partnerships with real estate firms and tech providers are becoming essential.The future of retail isn’t in fighting e-commerce—it’s in redefining the physical store’s role. Institutional planning ensures that stores remain relevant, profitable, and indispensable. For those willing to invest in the process, the rewards are substantial: higher valuations, lower risk, and a retail portfolio that thrives in any economic climate.
Comprehensive FAQs
Q: What’s the biggest misconception about retail planning institutional stores?
A: Many assume it’s only for large retailers like Walmart or Amazon. In reality, even mid-sized brands (e.g., local grocery chains) can adopt institutional planning principles by focusing on high-footfall locations, long-term leases, and data-driven tenant selection. The key is scalability—not brand size.
Q: How does institutional retail planning affect small businesses?
A: While institutional stores dominate prime locations, they create opportunities for small businesses through secondary tenant roles (e.g., boutique shops in a mall anchored by Macy’s). The trade-off? Small businesses must now compete for space in a more curated, high-service environment.
Q: Can a single store be "institutional" if it’s not part of a portfolio?
A: Technically yes, but the benefits diminish. Institutional planning relies on portfolio effects—like shared supply chains or cross-store promotions. A standalone store can mimic some aspects (e.g., long leases, high-tech POS), but the full advantage comes from systemic integration.
Q: What role does sustainability play in institutional retail planning?
A: Sustainability is now a non-negotiable factor. Institutional investors demand LEED-certified stores, zero-waste supply chains, and energy-efficient designs. Stores that fail to meet ESG (Environmental, Social, Governance) criteria risk higher cap rates and tenant turnover.
Q: How do rising interest rates impact institutional retail planning?
A: Higher rates increase financing costs for both retailers and landlords, making long-term leases more expensive. Institutional planners counter this by negotiating shorter initial terms (5–7 years) with built-in rate locks or tying rent increases to inflation-adjusted benchmarks.
Q: What’s the most underrated tool in retail planning institutional stores?
A: Consumer journey mapping—tracking how shoppers move through a store (not just sales data). Tools like heatmap analysis and dwell-time sensors reveal which product placements drive impulse buys, allowing retailers to optimize layouts for maximum profitability.
Q: How do international markets differ in institutional retail planning?
A: In markets like China or the Middle East, institutional planning must account for cultural nuances (e.g., longer store hours, family-centric layouts) and regulatory hurdles (e.g., foreign ownership restrictions). Lease structures also vary—some regions favor percentage rent over fixed rents to align tenant and landlord incentives.
Q: Can AI fully replace human intuition in retail planning?
A: No. AI excels at crunching data (e.g., predicting foot traffic spikes), but human intuition is critical for qualitative factors—like assessing a neighborhood’s vibe or negotiating lease terms. The future lies in hybrid models where AI handles analytics and humans make strategic calls.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of versiliasolutions.oneagency.co.